How to prepare Profit and Loss Statements?
On this page 55 sections
The Night I Almost Lost My Business: A Complete Guide to Preparing Profit and Loss Statements
I’ll never forget the evening I sat across from my banker, sweating through my shirt despite the air conditioning, fumbling through a stack of receipts and invoices. He’d asked for a simple P&L statement to review my loan application, and I realized I had no idea how to put one together. That embarrassing moment taught me something crucial: you can run a business without knowing how to prepare a profit and loss statement, but you can’t run it well.
If you’re here, you might be facing a similar situation – maybe your accountant is asking for financial statements, an investor wants to see your numbers, or you simply want to understand where your money is going. Don’t worry. I’ve been there, and I’m going to walk you through everything you need to know about preparing P&L statements, step by step.
What Exactly Is a Profit and Loss Statement?
A Profit and Loss (P&L) Statement, also called an income statement, is essentially a financial report card for your business. It shows how much money came in (revenue), how much went out (expenses), and what’s left over (profit or loss) during a specific time period – usually monthly, quarterly, or annually.
Think of it like a movie of your business finances, rather than a snapshot. While a balance sheet shows what you own and owe at one moment in time, the P&L tells the story of how your business performed over weeks or months.
Here’s what makes P&L statements so valuable: they reveal patterns you might miss in day-to-day operations. You might think you’re doing well because you’re busy, but the P&L shows whether that busyness translates to actual profit.
Let me share a real example from my consulting days. I had a client who ran a small bakery. Her revenue was $15,000 monthly, but she was always stressed about money. When we prepared her first P&L, we discovered her ingredient costs (COGS) were $6,000, leaving $9,000 gross profit. But her operating expenses – rent, utilities, wages, insurance – totaled $8,500. Her actual monthly profit? Just $500.
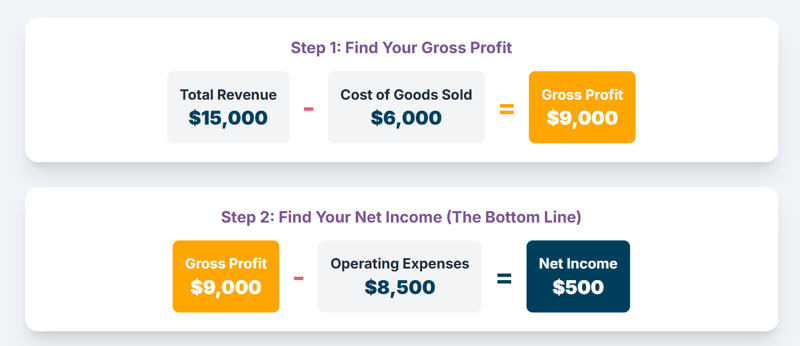
- Revenue (all money coming in)
- Minus Cost of Goods Sold (direct costs to make your product or service)
- Equals Gross Profit
- Minus Operating Expenses (rent, salaries, marketing, utilities)
- Equals Net Income (your actual profit or loss)
That P&L revealed why she felt broke despite good sales. It also showed exactly where to focus: either increase prices, reduce ingredient costs, or cut operating expenses.
Why Every Small Business Owner Needs to Master P&L Statements
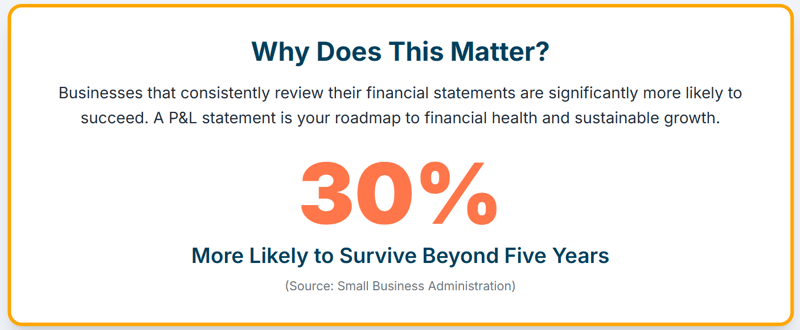
After helping dozens of small businesses over the years, I’ve seen the same pattern repeatedly: businesses that regularly prepare and review P&L statements make better decisions and survive longer. According to the Small Business Administration, companies that consistently review financial statements are 30% more likely to survive beyond five years.
Here’s why P&L statements matter so much:
They reveal hidden profit drains. You might not realize that your marketing spend increased 40% over six months, or that your cost of goods sold is creeping up due to supplier price increases.
They help with pricing decisions. When you see your true costs laid out, you can price your products or services appropriately instead of guessing.
They’re essential for growth planning. Want to hire someone? The P&L shows whether you can afford it. Thinking about expanding? You’ll need P&L projections for any loan or investment.
They satisfy legal and tax requirements. Whether it’s your accountant, the tax authorities, or potential lenders, everyone wants to see P&L statements.
I learned this importance the hard way. In my early business days, I operated mostly by gut feeling and bank balance. When a major client delayed payment for three months, I nearly ran out of cash because I hadn’t been tracking my true monthly expenses. A proper P&L would have shown me I needed three months of operating expenses in reserve.
Understanding the Key Components of a P&L Statement
Let me break down each section of a P&L statement using language that actually makes sense:
Revenue (The Money Coming In)
Revenue includes all income from your main business activities. For a restaurant, it’s food sales. For a consultant, it’s fees charged. For an online store, it’s product sales.
Important note: Record revenue when you earn it, not necessarily when you receive payment. If you invoice a client in March but they pay in April, that revenue belongs in March’s P&L.
Include these revenue sources:
- Primary sales or service income
- Secondary income (like a bakery selling coffee)
- Interest earned on business accounts
- Any other business-related income
Cost of Goods Sold (COGS) – Your Direct Costs
COGS represents the direct costs of creating whatever you sell. These costs rise and fall with your sales volume.
For different business types, COGS includes:
- Manufacturers: Raw materials, direct labor, factory overhead
- Retailers: Purchase price of inventory sold
- Restaurants: Food ingredients, beverage costs
- Service businesses: Direct labor costs for billable work
Here’s a key distinction I wish someone had explained to me earlier: if removing the cost would make it impossible to deliver your product or service, it’s probably COGS. If you could still deliver (but less efficiently), it’s likely an operating expense.
Gross Profit – Your First Profit Indicator
Gross profit equals revenue minus COGS. This number tells you how much money you have left to cover all your other business expenses.
Your gross profit margin (gross profit divided by revenue) is crucial for benchmarking. Different industries have different typical margins:
- Software companies: 70-90%
- Restaurants: 60-70%
- Retail: 20-50%
- Manufacturing: 25-35%
If your gross margin is significantly below industry standards, you need to either raise prices or reduce direct costs.
Operating Expenses – Everything Else
Operating expenses include all costs of running your business that aren’t directly tied to creating your product or service:
- Fixed expenses: Rent, insurance, base salaries, loan payments
- Variable expenses: Utilities, marketing, office supplies, professional services
- Administrative costs: Accounting, legal, banking fees, software subscriptions
I recommend categorizing these expenses consistently. Create categories that make sense for your business and stick with them month after month. This consistency makes it easier to spot trends and unusual expenses.
Net Income – Your Bottom Line
Net income is what remains after subtracting all expenses from revenue. This is your actual profit (or loss) for the period.
A positive number means you made money. A negative number means you spent more than you earned. Both scenarios are normal at different stages of business, but consistently negative numbers indicate problems that need addressing.
What Are the Main Benefits and Drawbacks of Regular P&L Preparation?
Benefits That Actually Matter
Improved cash flow management: You’ll spot seasonal patterns and plan accordingly. My retail clients often see revenue dips in January and February, but their P&L history helps them save cash during busy months.
Better vendor negotiations: When you know exactly how much you spend with suppliers, you have leverage for bulk discounts or better payment terms.
Informed hiring decisions: Instead of hiring when you’re busy and firing when you’re slow, P&L trends help you make sustainable staffing choices.
Investment readiness: Whether seeking loans or investors, you’ll have the financial documentation they require.
Potential Drawbacks
Time investment: Preparing monthly P&L statements takes 2-4 hours initially, though this decreases with practice and good systems.
Learning curve: Understanding accounting principles like accrual vs. cash basis takes time, especially for non-financial business owners.
Emotional stress: Seeing losses in black and white can be discouraging, particularly during difficult periods.
Complexity for multi-revenue businesses: If you have several income streams, categorizing and tracking everything becomes more complex.
Honestly, the benefits far outweigh the drawbacks. But I won’t sugarcoat it – there’s real work involved in doing this properly.
When Should You Prepare P&L Statements?
Frequency Recommendations
Monthly: Ideal for most small businesses. Gives you timely information for decision-making without being overwhelming.
Quarterly: Minimum frequency for very small businesses or startups with limited activity.
Weekly: Only necessary for businesses with rapid changes or tight cash flow situations.
Annually: Not sufficient for active management, though you’ll need annual statements for taxes and loan applications.
I’ve found monthly preparation hits the sweet spot. It’s frequent enough to catch problems early but not so frequent that it becomes burdensome.
Specific Situations Requiring P&L Statements
- Loan applications (banks typically want 3 years of statements)
- Investor presentations (monthly or quarterly statements showing trends)
- Tax preparation (your accountant needs annual statements)
- Business valuations (buyers want detailed financial history)
- Partnership discussions (transparent financials build trust)
- Performance reviews with key employees (helps them understand business health)
Step-by-Step Guide to Preparing Your First P&L Statement
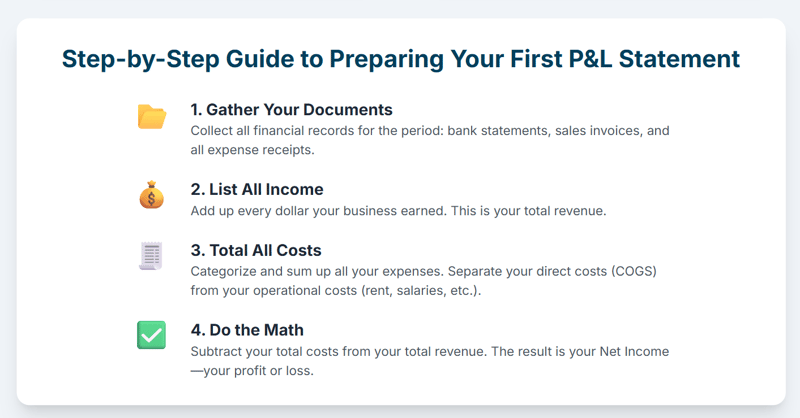
Let me walk you through the actual process I use with my clients:
Step 1: Gather Your Financial Data
You’ll need:
- Bank statements for the period
- Sales records or invoices issued
- Receipt files or expense records
- Payroll records
- Inventory information (if applicable)
Pro tip: If your records are messy, start with last month and commit to better organization going forward. Don’t try to recreate two years of history – you’ll get overwhelmed and quit.
Step 2: Choose Your Accounting Method
Cash basis: Record income when received, expenses when paid. Simpler but less accurate for businesses with significant receivables or payables.
Accrual basis: Record income when earned, expenses when incurred. More accurate but requires tracking invoices and bills separately from cash flow.
Most small businesses start with cash basis and switch to accrual as they grow. Choose based on your business complexity and legal requirements.
Step 3: Organize Revenue
List all income sources:
- Primary business revenue
- Secondary income streams
- Interest or investment income
- Any other business-related income
Example for a consulting business:
- Consulting fees: $8,500
- Workshop revenue: $1,200
- Affiliate commissions: $150
- Total Revenue: $9,850
Step 4: Calculate Cost of Goods Sold
Identify and total your direct costs:
For service businesses:
- Direct labor costs for billable work
- Subcontractor payments
- Direct materials used
For product businesses:
- Beginning inventory + purchases - ending inventory
- Direct labor
- Direct materials
Example for the same consulting business:
- Subcontractor fees: $2,000
- Direct research costs: $300
- Total COGS: $2,300
Step 5: List Operating Expenses
Categorize all other business expenses:
Fixed expenses:
- Office rent: $1,200
- Insurance: $200
- Software subscriptions: $150
Variable expenses:
- Marketing: $400
- Utilities: $180
- Office supplies: $75
- Professional development: $200
Total Operating Expenses: $2,405
Step 6: Calculate Your Results
Using our consulting example:
- Revenue: $9,850
- Less COGS: $2,300
- Gross Profit: $7,550
- Less Operating Expenses: $2,405
- Net Income: $5,145
This business had a healthy 52% net profit margin for the month.
Common Mistakes to Avoid (I’ve Made Most of These)
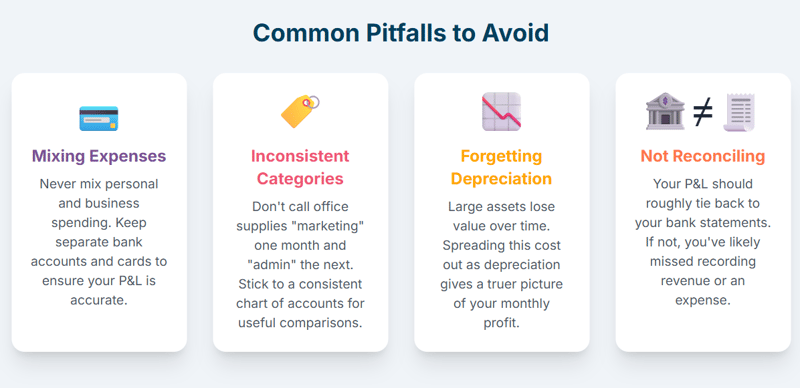
Mixing Personal and Business Expenses
I once spent hours trying to figure out why my restaurant client’s food costs seemed so high, only to discover he was including his family’s groceries in the business expenses. Keep separate accounts and credit cards for business use.
Inconsistent Categorization
Don’t put office supplies under “marketing” one month and “administrative” the next. Create a chart of accounts and stick to it. Your P&L is only useful if you can compare periods accurately.
Ignoring Timing Issues
A common mistake is recording large, one-time expenses in a single month, which distorts that month’s results. Consider spreading large expenses over multiple months or noting them separately as non-recurring items.
Forgetting Depreciation
If you bought equipment, vehicles, or other assets, you should include depreciation expense rather than the full purchase price. This gives a more accurate picture of monthly costs.
Not Reconciling with Bank Statements
Your P&L should tie back to your actual cash flow, adjusted for timing differences. If there are major discrepancies, you’ve likely missed something important.
Advanced Tips for More Accurate P&L Statements
Handling Seasonal Businesses
If your business has seasonal fluctuations, prepare rolling 12-month P&L statements alongside monthly ones. This smooths out seasonal variations and shows true business trends.
Managing Inventory-Heavy Businesses
For businesses with significant inventory, accurate COGS calculation requires careful inventory tracking. Consider using inventory management software that integrates with your accounting system.
Dealing with Multiple Revenue Streams
If you have several distinct income sources, consider preparing separate P&L statements for each major revenue stream. This helps identify which parts of your business are most profitable.
Incorporating Non-Cash Expenses
Include non-cash expenses like depreciation and amortization for a complete picture of business performance. These don’t affect cash flow but represent real economic costs.
Using Technology to Streamline P&L Preparation
Accounting Software Benefits
Modern accounting software can automate much of the P&L preparation process. Systems like QuickBooks, Xero, or ProfitBooks can:
- Automatically categorize expenses
- Generate P&L statements with one click
- Track inventory and calculate COGS
- Integrate with bank accounts for automatic transaction import
I’ve seen business owners reduce P&L preparation time from 4 hours to 30 minutes by implementing proper accounting software.
Integration with Banking
Most accounting platforms now connect directly to business bank accounts, automatically importing transactions. This reduces manual data entry and improves accuracy.
Mobile Expense Tracking
Use mobile apps to photograph receipts immediately. Many integrate with accounting software, automatically categorizing expenses and storing receipt images.
A personal note: I resisted accounting software for years, thinking it was overkill for my small business. Once I finally made the switch, I wondered why I’d wasted so much time on manual spreadsheets. The time savings alone paid for the software cost within two months.
Analyzing Your P&L for Business Insights
Key Ratios to Track
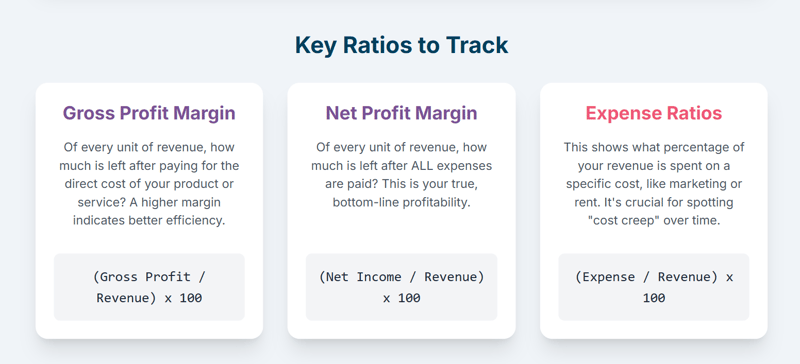
Gross Profit Margin: Gross profit ÷ revenue. Shows how efficiently you deliver your core product or service.
Net Profit Margin: Net income ÷ revenue. Reveals overall business profitability.
Expense Ratios: Each major expense category ÷ revenue. Helps identify cost creep over time.
Month-to-Month Comparisons
Look for trends rather than focusing on single-month results:
- Is revenue growing consistently or erratically?
- Are expense categories growing faster than revenue?
- Do you see seasonal patterns you can plan around?
Benchmarking Against Industry Standards
Research typical financial ratios for your industry. If your gross margin is significantly below average, investigate whether it’s due to pricing, efficiency, or cost structure issues.
What to Do When Your P&L Shows a Loss
Don’t panic – losses happen, especially in new businesses or during difficult periods. Here’s how to respond constructively:
Immediate Actions
- Verify accuracy: Double-check your numbers. Are all expenses correctly categorized? Did you miss any revenue?
- Identify controllable factors: Separate temporary issues (like delayed client payments) from structural problems (like pricing too low).
- Prioritize expenses: List all expenses by necessity. What can you cut immediately without damaging long-term prospects?
Longer-term Strategies
- Revenue enhancement: Can you raise prices, add services, or find new revenue streams?
- Cost optimization: Look for ways to reduce COGS or operating expenses without harming quality.
- Cash flow management: Even profitable businesses fail due to cash flow problems. Ensure you have adequate working capital.
Industry-Specific P&L Considerations
Service Businesses
Focus heavily on utilization rates and billing efficiency. Your main COGS is typically labor, so track how much time you can bill versus total time worked.
Retail Businesses
Inventory management is crucial. Your COGS calculation must account for inventory shrinkage, seasonal markdowns, and obsolete stock.
Manufacturing
Track both direct and indirect manufacturing costs carefully. Consider using job costing to understand profitability by product line.
Restaurants and Food Service
Food costs typically run 28-35% of revenue. Labor costs (including benefits) usually run 30-35%. If your combined food and labor costs exceed 65% of revenue, you’ll struggle to be profitable.
Building P&L Forecasts for Planning
Once you’re comfortable with historical P&L statements, try creating forward-looking projections:
Revenue Forecasting
Base projections on:
- Historical trends
- Known upcoming contracts or orders
- Seasonal patterns
- Market conditions
Expense Planning
Most expenses fall into predictable patterns:
- Fixed expenses remain constant
- Variable expenses correlate with revenue
- Step-function expenses increase at certain revenue thresholds
Scenario Planning
Create multiple P&L projections:
- Conservative: Lower revenue, higher expenses
- Realistic: Most likely scenario
- Optimistic: Higher revenue growth
This helps you plan for different outcomes and identify potential cash flow needs.
Frequently Asked Questions
How often should I prepare P&L statements? Monthly is ideal for most small businesses. It provides timely information without being overwhelming.
What’s the difference between cash and accrual accounting for P&L statements? Cash basis records transactions when money changes hands; accrual records them when earned or incurred. Accrual gives a more accurate picture of business performance.
Should I include owner’s salary in the P&L? Yes, if you’re paying yourself a regular salary. This shows the true cost of operating the business.
How do I handle large, one-time expenses? You can record them in the month incurred but note them as non-recurring items, or spread them over multiple months if they benefit multiple periods.
What if my P&L doesn’t match my cash flow? This is normal with accrual accounting. Revenue and expenses are recorded when earned/incurred, not when cash is received/paid.
Can I prepare P&L statements myself, or do I need an accountant? You can prepare basic P&L statements yourself, especially with modern accounting software. Consider an accountant for complex situations or tax planning.
What’s a good profit margin for small businesses? It varies by industry, but 10-20% net profit margin is generally healthy for small businesses.
How do I categorize expenses that could fit multiple categories? Choose one category and stick with it consistently. The key is consistency over perfect categorization.
Should I include depreciation in my P&L? Yes, depreciation represents the real cost of using business assets and should be included for accurate profitability measurement.
What do I do if my P&L shows consistent losses? Analyze whether losses are due to startup costs, seasonal factors, or structural problems. Consider pricing adjustments, cost reductions, or strategic changes.
Conclusion
Preparing profit and loss statements might seem daunting at first, but it’s one of the most valuable skills you can develop as a business owner. These financial reports provide the clarity and insights needed to make informed decisions, whether you’re just starting out or running an established business.
Remember, your first P&L statement doesn’t need to be perfect. The important thing is to start. As you develop the habit of regular P&L preparation, you’ll gain confidence and catch mistakes that could cost you thousands of dollars.
For startups and small businesses, focus on consistency over complexity. Use simple categories, maintain good records, and review your results monthly. As your business grows, you can always add more sophisticated analysis and reporting.
The goal isn’t to become an accountant – it’s to understand your business well enough to make smart decisions. Every hour you invest in learning P&L preparation will pay dividends in better business outcomes.
If you’re feeling overwhelmed by the manual work involved in preparing P&L statements, consider using accounting software designed for non-accountants. ProfitBooks, for example, can automatically generate professional P&L statements from your business transactions, saving hours of manual work while ensuring accuracy. The time you save can be invested in analyzing the results and improving your business.
Start with next month’s P&L statement. Gather your records, choose your categories, and work through the process step by step. You’ll be surprised how much you learn about your business – and how much more confident you feel making financial decisions.
Your business deserves the clarity that comes from proper financial reporting. Take the first step today, and you’ll thank yourself later when you’re sitting across from that banker or investor, confidently discussing your business performance with a professional P&L statement in hand.