Cash Flow vs Profit: What’s the Difference for Small Businesses?
On this page 25 sections
The profitable business with no cash
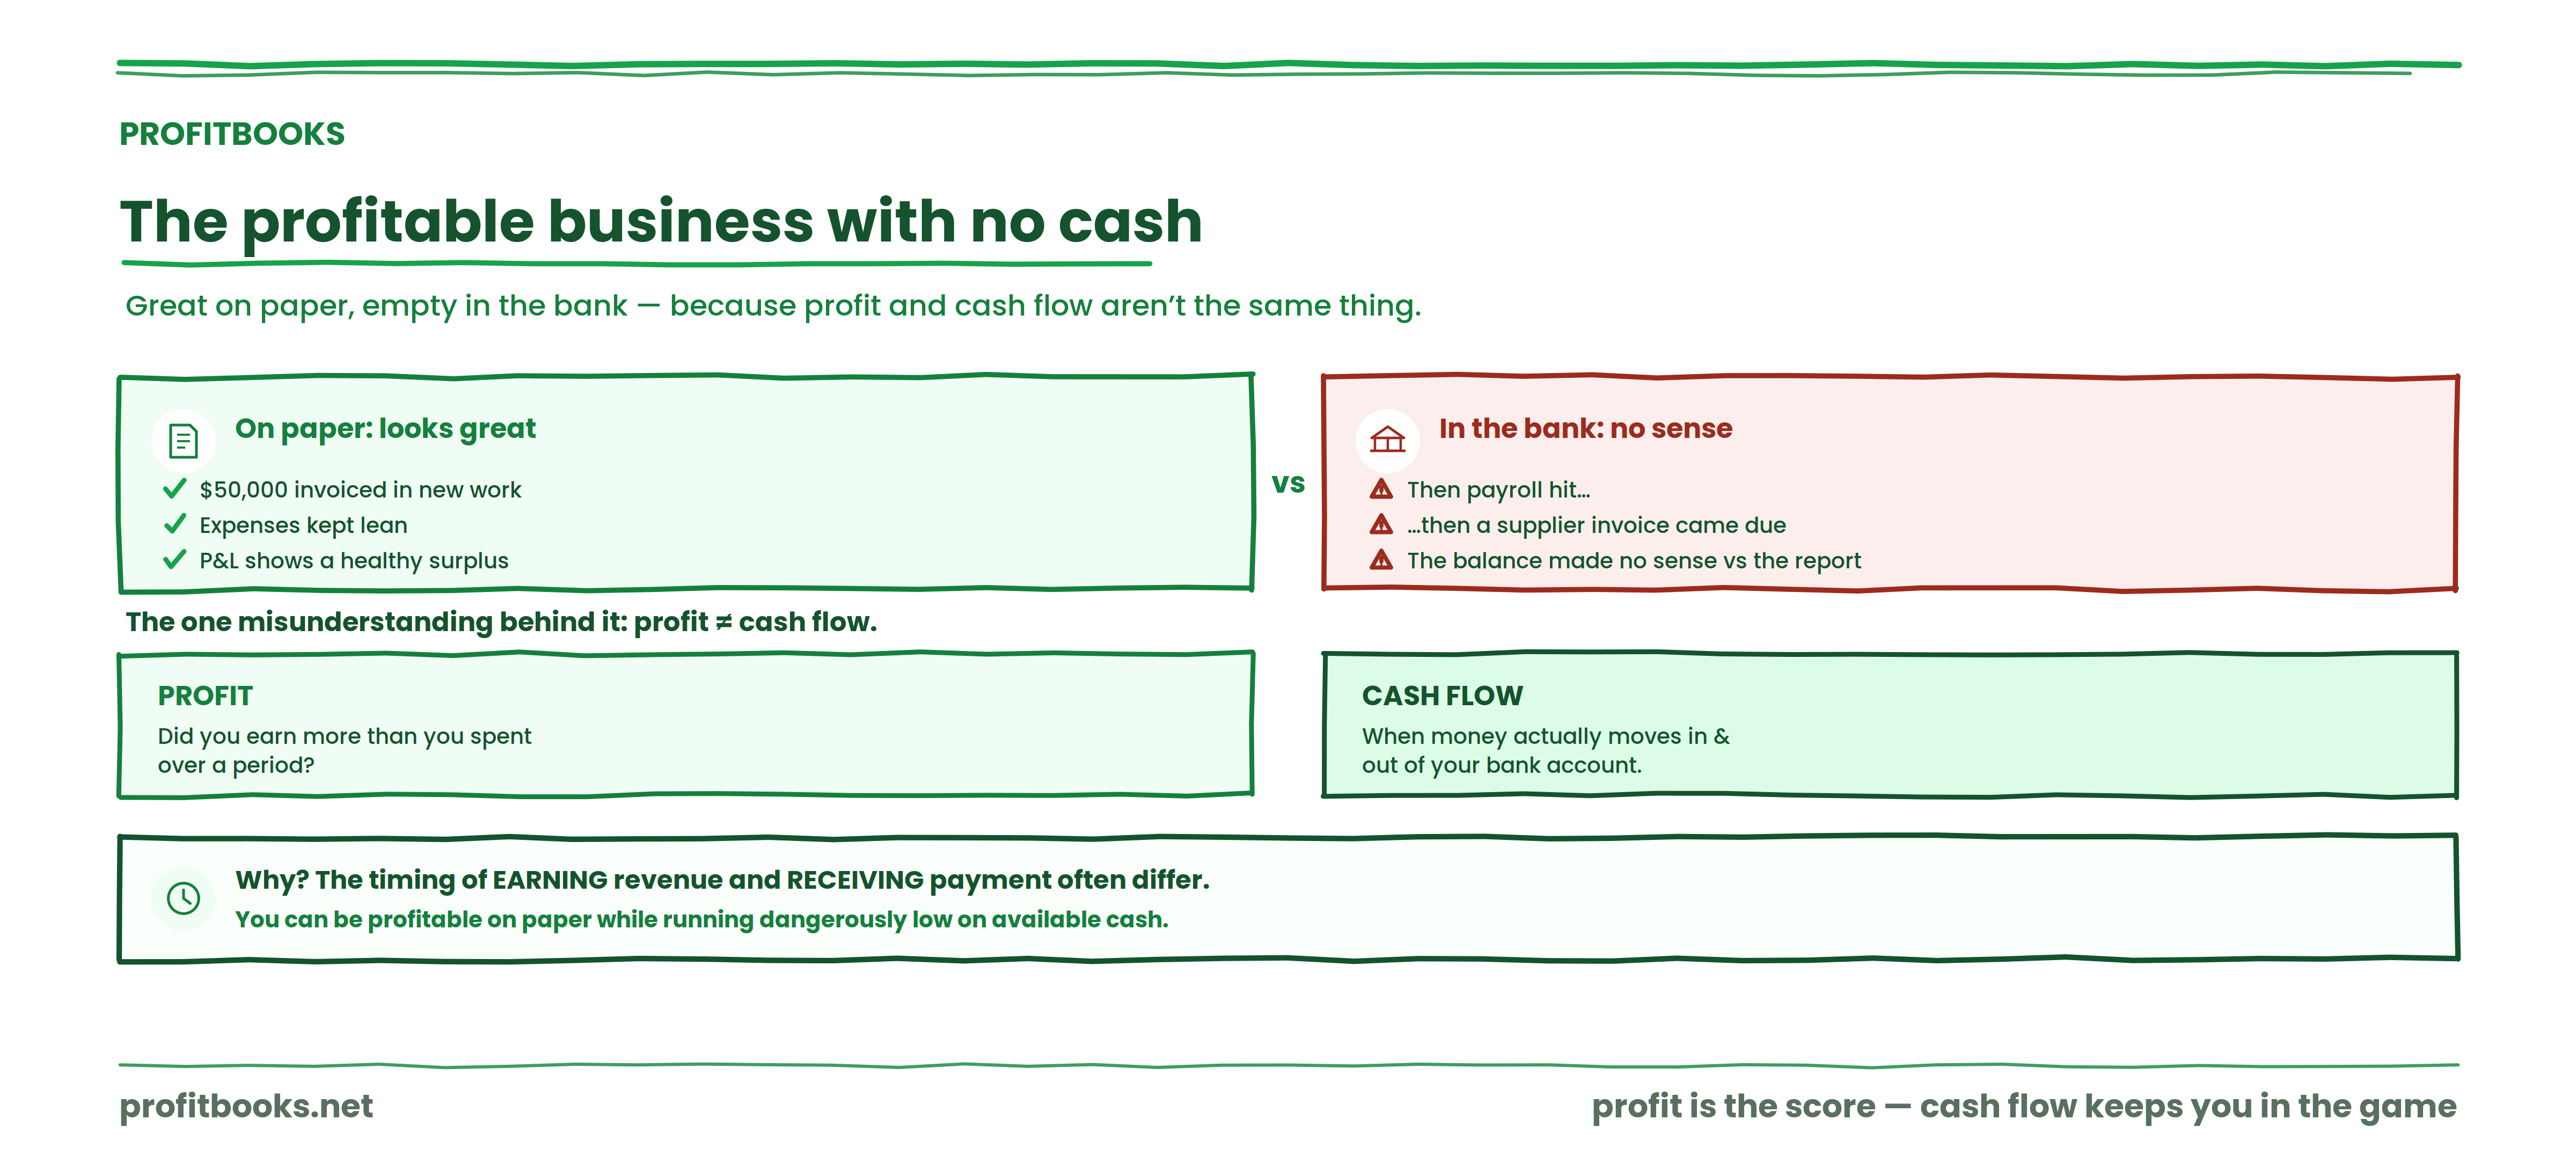
Last quarter looked great on paper. You invoiced $50,000 in new work, kept expenses lean, and your profit and loss statement showed a healthy surplus. Then payroll hit. Then a supplier invoice came due. You opened your bank account and stared at a number that made no sense against the report you’d just reviewed.
Sound familiar?
This is one of the most common and most stressful problems small business owners face. And it often comes down to one misunderstanding: cash flow vs profit are not the same thing.
Here is the short answer. Cash flow vs profit comes down to two different ways of looking at your business finances. Profit measures whether your business earned more than it spent during a period. Cash flow tracks when money actually moves into and out of your bank account.
A business can be profitable on paper while running dangerously low on available cash because the timing of earning revenue and receiving payment are often very different
Now let's go deeper, because that short answer alone won't fix the problem.
What is the difference between cash flow and profit?
Profit answers: Did my business create more value than it consumed?
Cash flow answers: Does my business have enough money available right now to operate?
Profit is calculated from revenue and expenses, regardless of when the actual cash changed hands. Cash flow reflects the real movement of money. You can record a $10,000 sale today and show it as revenue immediately, but if the customer pays in 60 days, your cash flow doesn't see that money for two months.
This single timing gap is the root cause of most confusion between the two.
Cash flow vs profit: a quick comparison
| Profit | Cash Flow | |
|---|---|---|
| What it measures | Financial earnings over a period | Actual cash entering and leaving the business |
| Based on | Revenue minus expenses | Cash received minus cash paid out |
| Key question it answers | Is the business financially viable? | Can the business pay its bills today? |
| Can be positive while the other is negative? | Yes | Yes |
| Primary report | Profit and loss statement (income statement) | Cash flow statement |
Both numbers matter. Neither tells the full story alone.
What is profit?
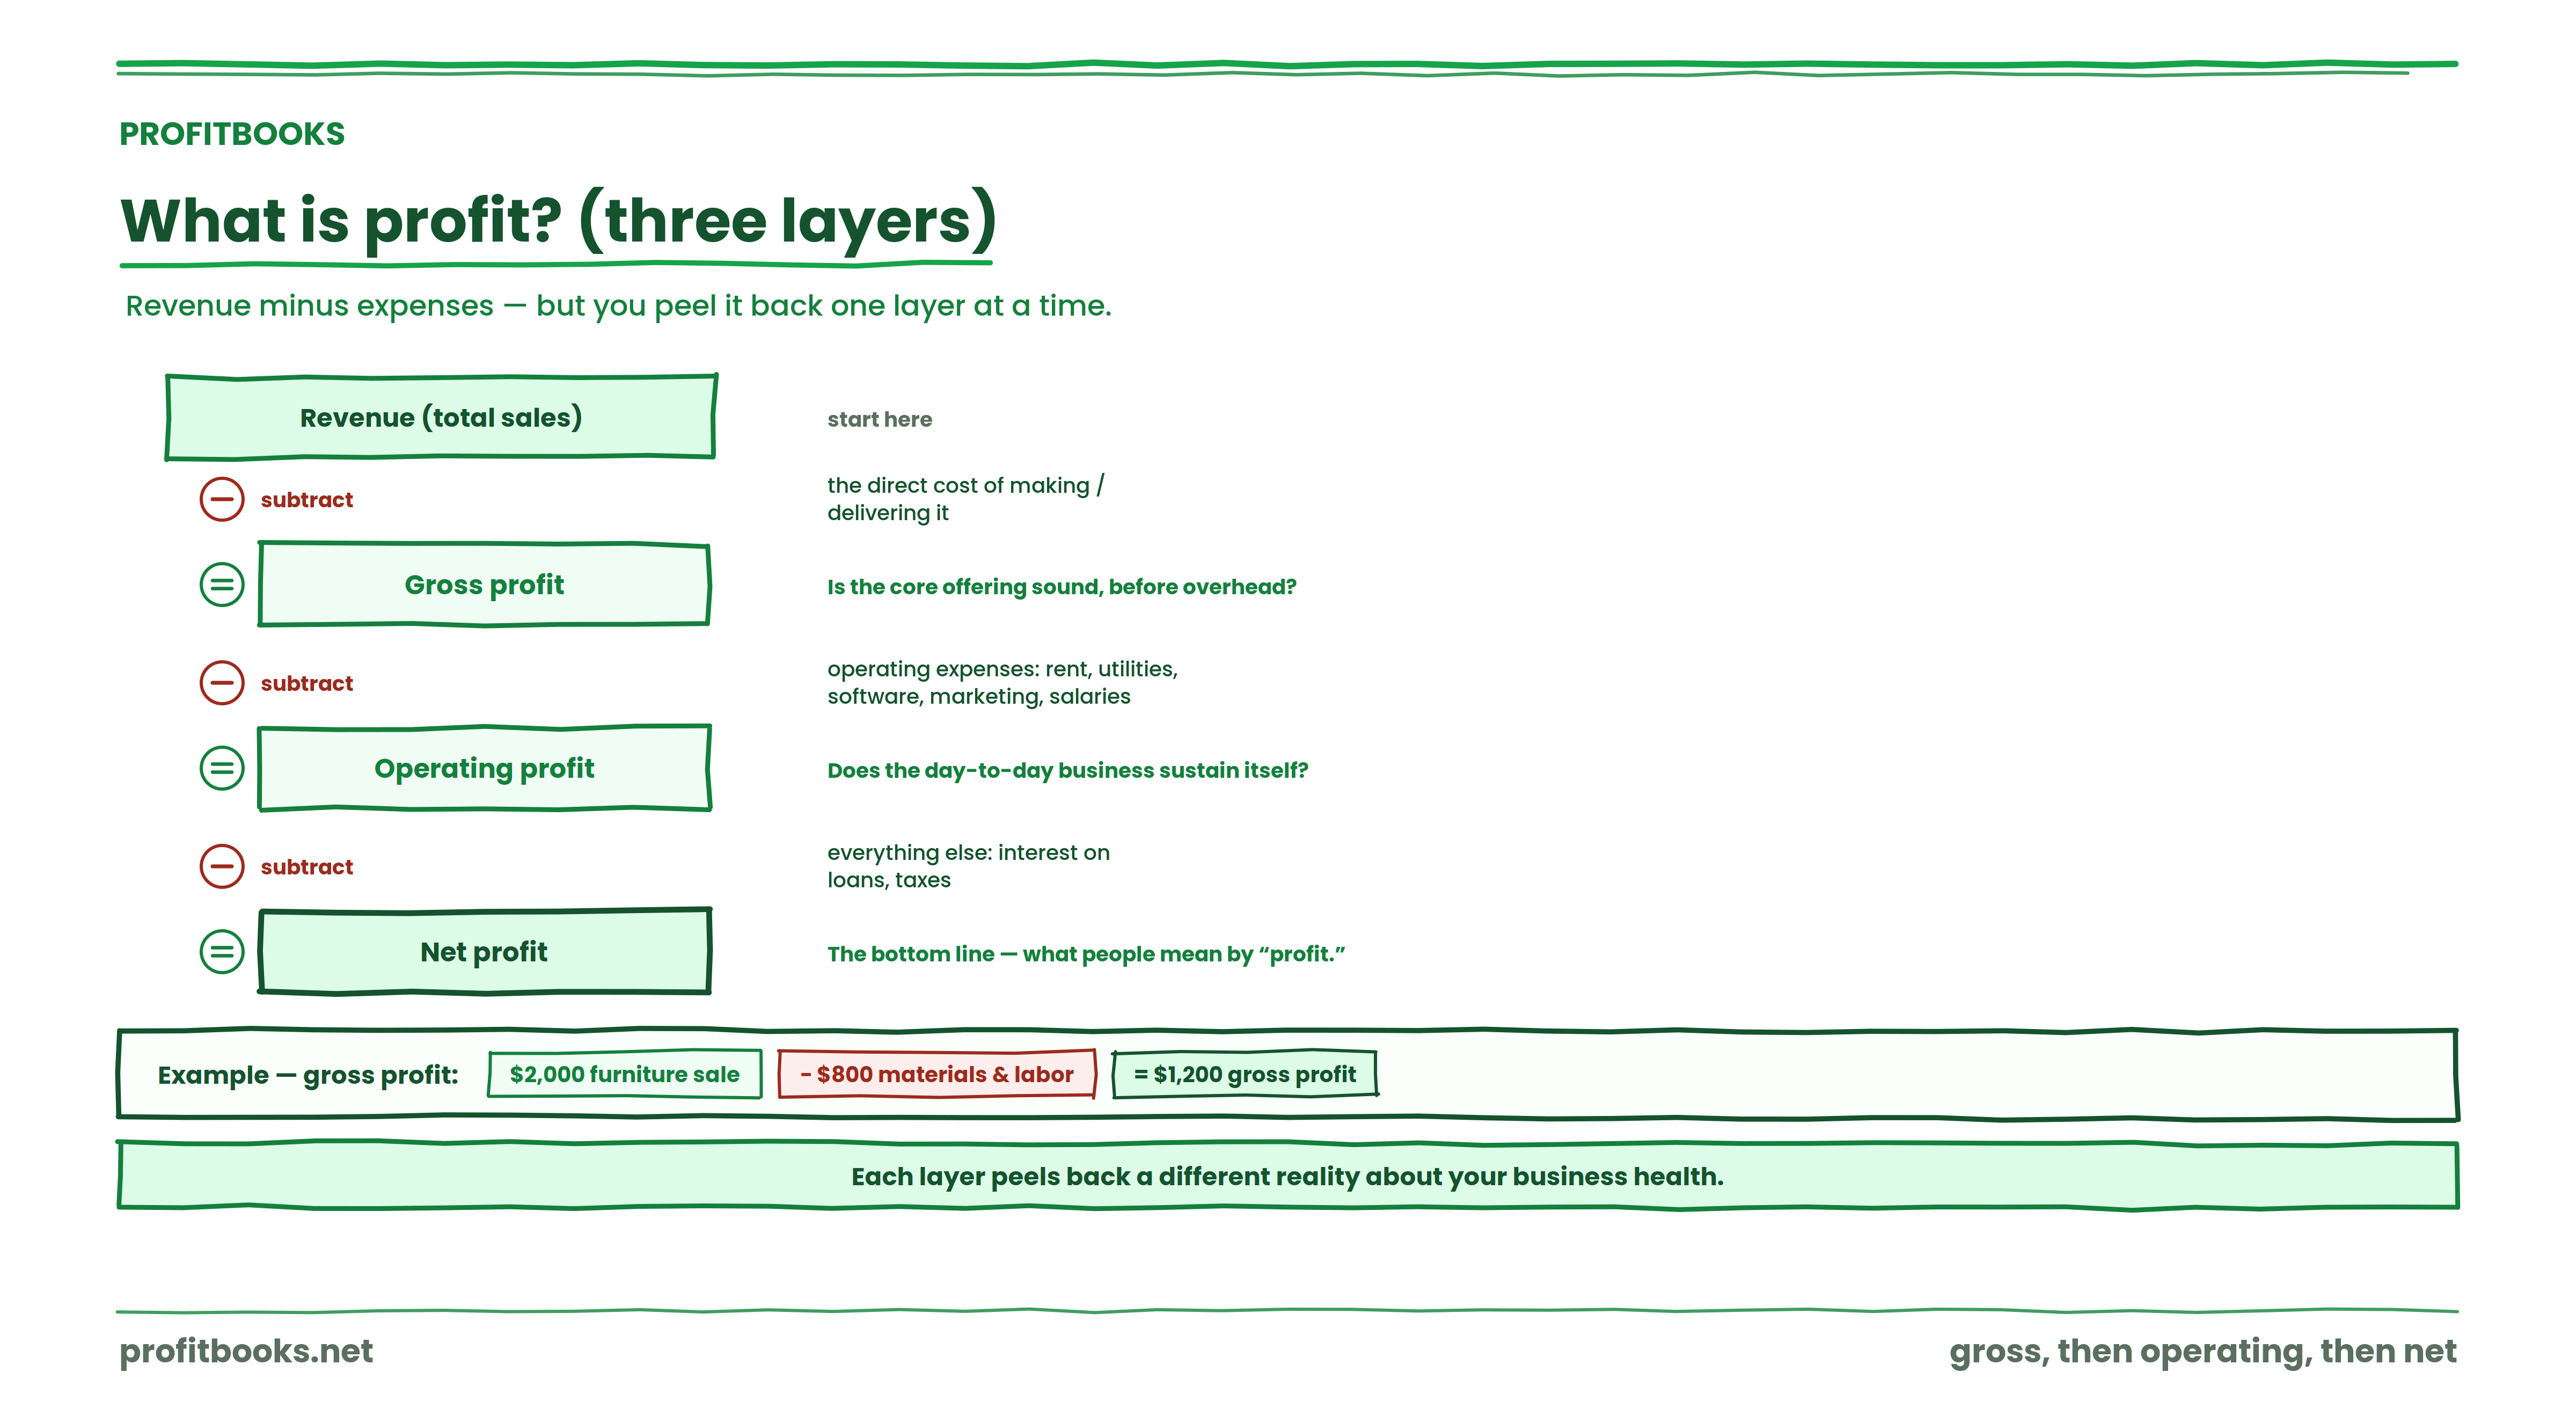
Profit is what remains after you subtract your business expenses from your revenue. But "profit" itself has layers.
Gross profit
Revenue minus the direct cost of producing your product or delivering your service. If you sell handmade furniture for $2,000 and the materials and labor cost $800, your gross profit is $1,200. This tells you whether your core offering is financially sound before overhead enters the picture.
Operating profit
Gross profit minus your operating expenses: rent, utilities, software subscriptions, marketing, salaries. This shows whether the day-to-day business generates enough to sustain itself.
Net profit
Operating profit minus everything else: interest on loans, taxes, and any other costs. Net profit is the bottom line. It is the number most people mean when they simply say "profit."
Each layer peels back a different reality about your business health.
What is cash flow?
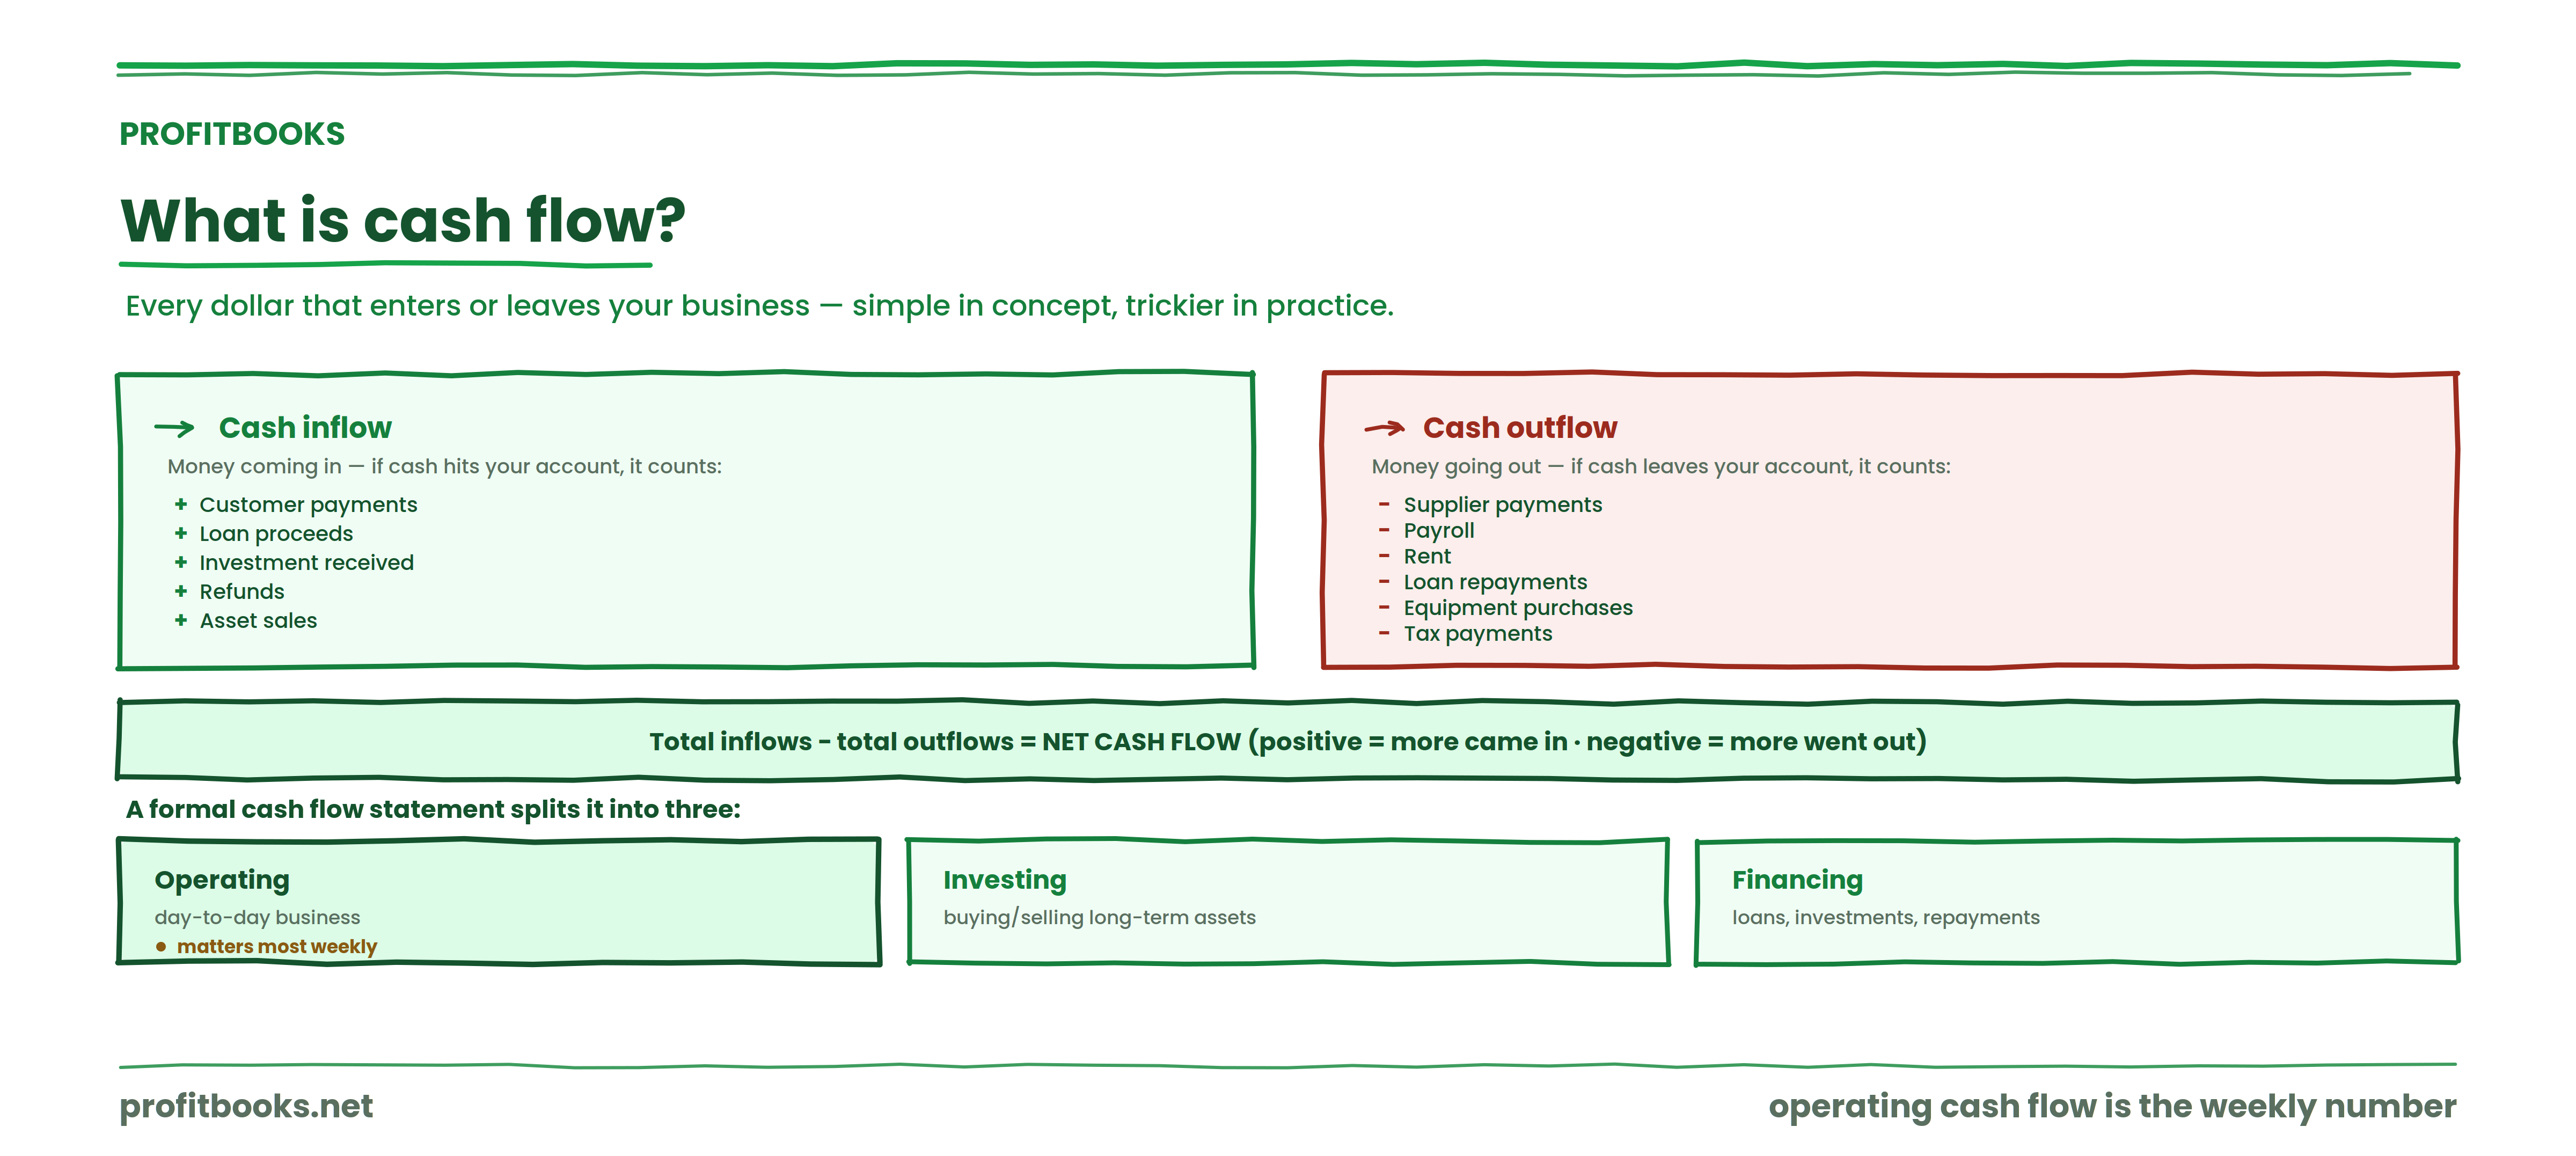
Cash flow is simpler in concept but trickier in practice. It tracks every dollar that enters or leaves your business.
Cash inflow
Money coming in. Customer payments, loan proceeds, investment received, refunds, asset sales. If cash hits your account, it counts.
Cash outflow
Money going out. Supplier payments, payroll, rent, loan repayments, equipment purchases, tax payments. If cash leaves your account, it counts.
The difference between total inflows and total outflows over a period is your net cash flow. Positive means more came in than went out. Negative means the opposite.
A formal cash flow statement typically breaks this into three categories: operating activities (day-to-day business), investing activities (buying or selling long-term assets), and financing activities (loans, investments, repayments). For most small business owners, operating cash flow is the number that matters most on any given week.
The Profit-to-Cash Gap: why the numbers don't always match
Here is the framework that makes this entire topic click.
When your profit report says one thing and your bank balance says another, there is a gap. I call it the Profit-to-Cash Gap. It is not a mystery. It comes from five predictable places.
1. Unpaid customer invoices
You completed the work. You sent the invoice. Your accounting software recorded the revenue. But the customer hasn't paid yet. That unpaid amount sits as accounts receivable. Your profit statement counts it. Your bank account does not.
I have watched businesses show $30,000 in monthly profit while carrying $25,000 in unpaid invoices past 45 days. That is a profitable business that cannot make payroll without a credit line.
2. Inventory
If you sell physical products, you likely buy inventory before you sell it. Cash leaves your business the moment you pay your supplier. But the expense is only recorded when the product is sold. In the meantime, your cash is locked inside boxes sitting on shelves.
Overstocking is one of the fastest ways to create a wide Profit-to-Cash Gap.
3. Supplier payment timing
Your suppliers may require payment in 15 days. Your customers may take 45 days to pay you. That 30-day mismatch means you are constantly paying out before collecting. Your profit doesn't reflect this timing strain. Your bank account absolutely does.
4. Loan payments
When you repay a business loan, the interest portion is recorded as an expense. But the principal repayment is not an operating expense in the traditional sense. It reduces your debt on the balance sheet, but it does not reduce your reported profit. Cash still leaves the business, though.
A $2,000 monthly loan payment where $500 is interest and $1,500 is principal means $1,500 disappears from your cash without showing up as a cost on your profit and loss statement.
5. Major business purchases
You buy a $24,000 piece of equipment. Cash leaves immediately. But under standard accounting, that equipment is depreciated over its useful life. If you depreciate it over four years, your profit and loss statement records only $6,000 per year as an expense, or $500 per month. Your cash flow felt the full $24,000 hit on day one.
These five sources account for nearly every case of "profitable but cash-poor" that I have encountered with small businesses.
Why can a profitable business still run out of cash?
Yes, a profitable business can absolutely run out of cash. It happens more often than most owners expect, especially during periods of rapid growth.
The most common triggers:
Growth, ironically, is one of the biggest cash flow killers. A business that doubles its sales often needs to double its upfront spending on inventory, staffing, and infrastructure before those new sales convert to collected cash.
Spot the Profit-to-Cash Gap before it becomes a crisis
ProfitBooks tracks invoices, outstanding receivables, and expense patterns in one place, so you can see the timing gap between profit and cash while there's still time to act.
Can a business have positive cash flow but no profit?
Yes, and this is just as important to understand.
A business might show positive cash flow while operating at a loss. This can happen when:
Positive cash flow from these sources can mask an unprofitable operation. That is why looking at both metrics together is essential.
Cash flow vs profit: a simple example
Imagine a small design agency in its first month:
On paper (profit)
Invoiced revenue: $20,000 across four clients
Expenses incurred: $14,000 (salaries, software, rent)
Profit on paper: +$6,000
In the bank (cash)
Cash received from clients: $8,000 (two paid; two will pay next month)
Cash paid out: $14,000 (all expenses due immediately)
Net cash flow: -$6,000
The agency is profitable. It also has negative cash flow. If it started the month with less than $6,000 in the bank, it cannot cover its obligations without borrowing or dipping into reserves.
This is not a hypothetical edge case. This is Tuesday for many small businesses.
Which is more important: cash flow or profit?
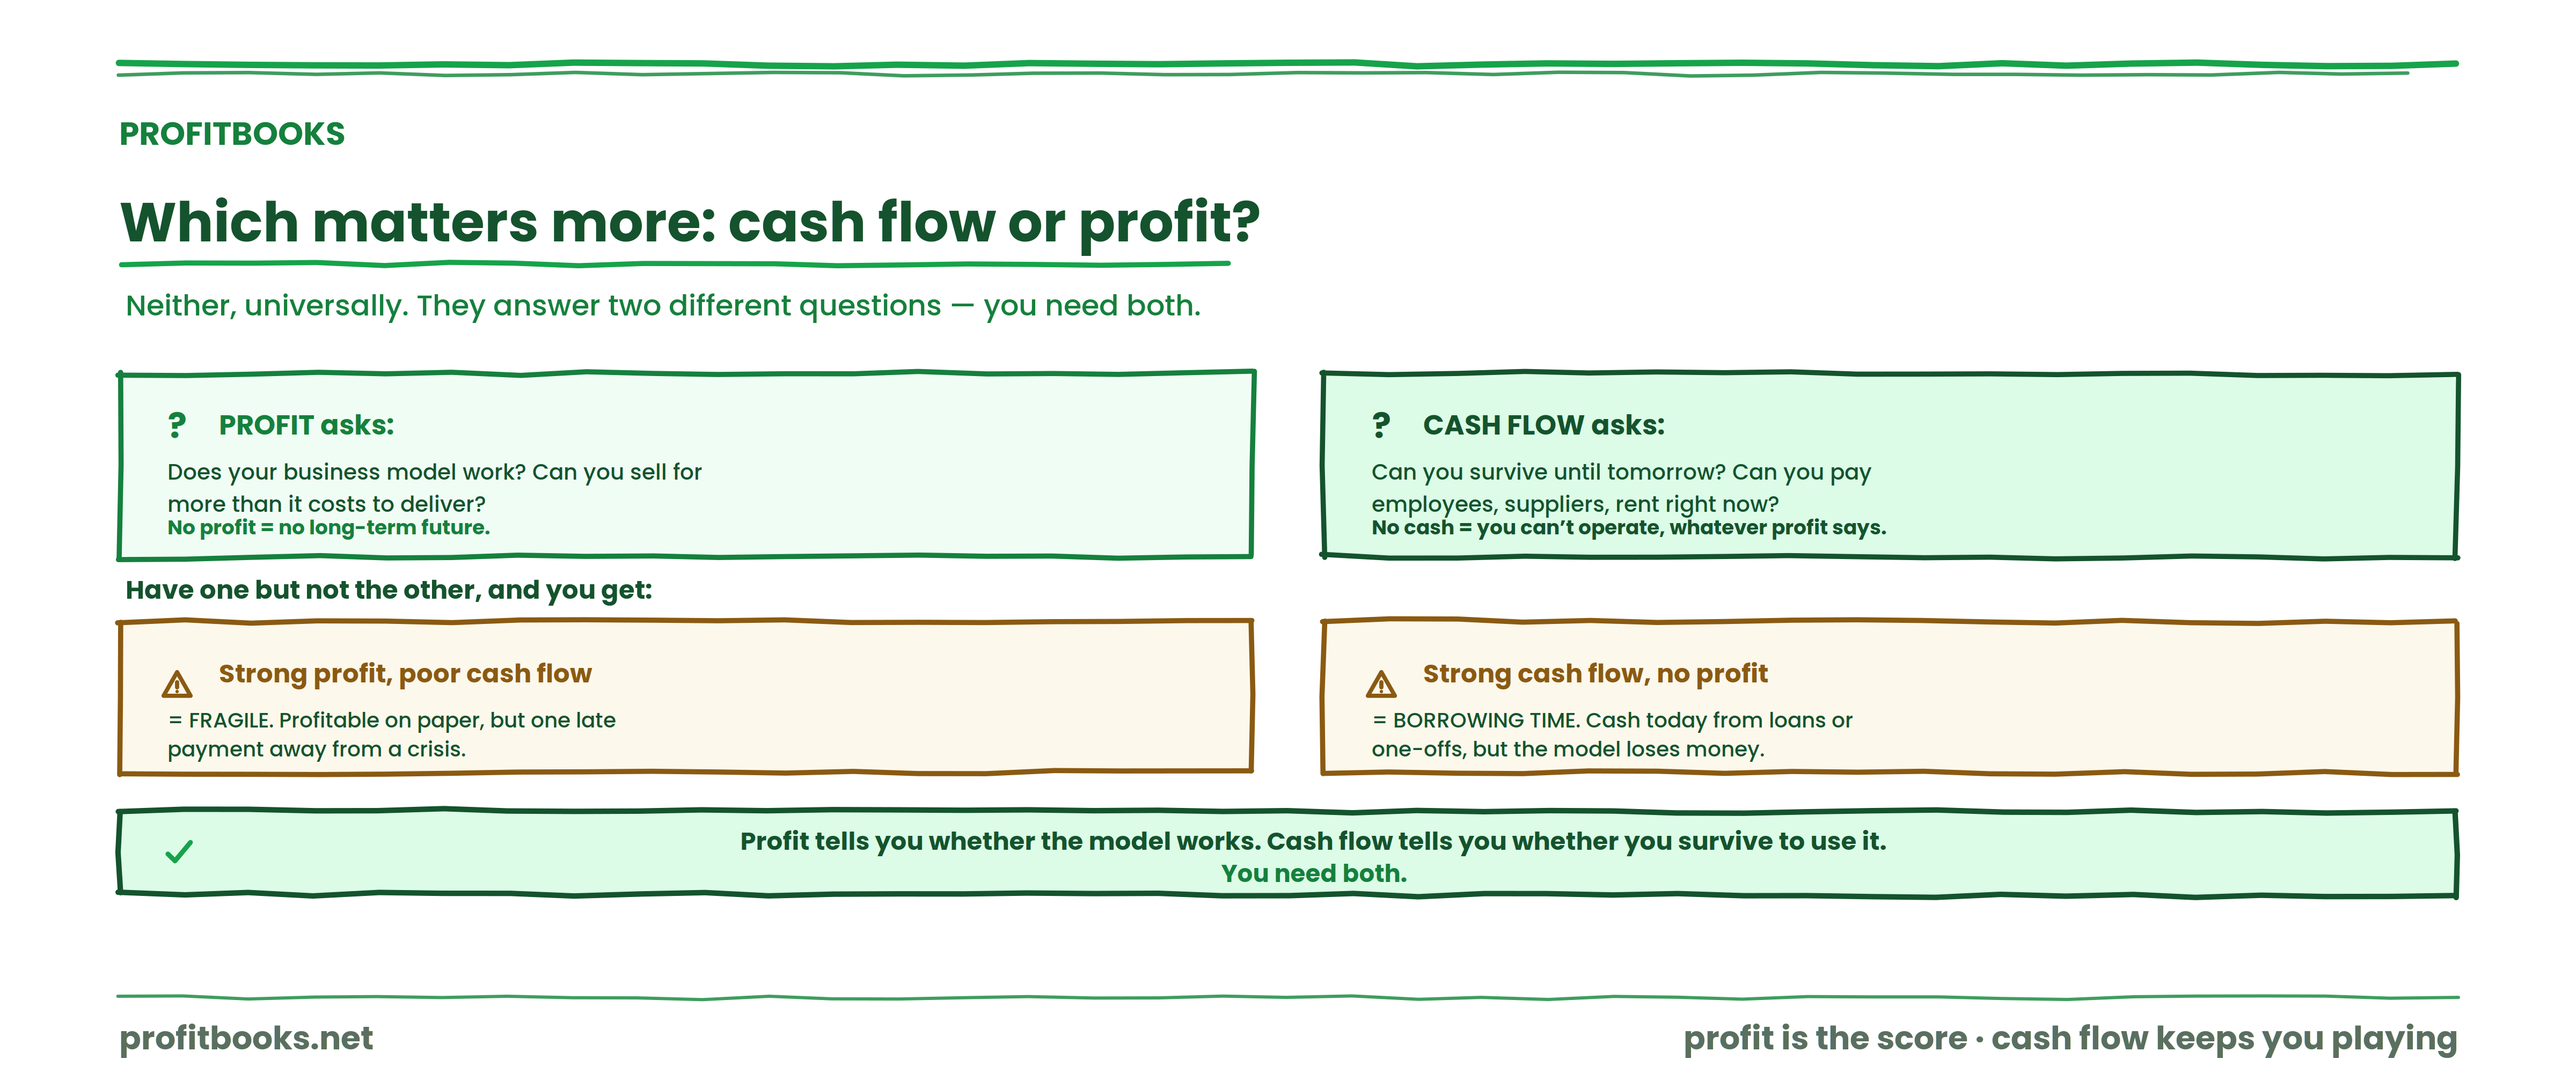
Neither is universally more important. They answer different questions.
Profit tells you whether your business model works. Can you sell your product or service for more than it costs to deliver? Without profit, a business has no long-term future.
Cash flow tells you whether you can survive until tomorrow. Without cash, a business cannot pay employees, suppliers, or rent, regardless of what the profit report says.
A business with strong profit but poor cash flow is fragile. A business with strong cash flow but no profit is borrowing time. You need both.
How can small businesses improve both profit and cash flow?
To improve profit
▸ Review pricing to ensure margins cover all costs
▸ Cut unnecessary expenses
▸ Focus on higher-margin products or services
▸ Reduce waste and inefficiency
To improve cash flow
▸ Invoice immediately after delivering work
▸ Shorten payment terms where possible
▸ Offer small incentives for early payment
▸ Negotiate longer payment terms with suppliers
▸ Avoid overstocking inventory
▸ Build a cash reserve for seasonal dips
▸ Monitor your working capital to understand short-term liquidity
How to monitor cash flow and profit more effectively
Checking your profit and loss report once a year at tax time is not enough. Small businesses benefit from reviewing profit monthly and monitoring cash flow weekly.
A simple weekly habit: check your expected inflows for the next 30 days against your committed outflows. If there is a gap, you have time to act. If you only discover the gap when a payment bounces, you have a crisis.
Cash flow forecasting does not require complex models. Even a basic spreadsheet projecting expected payments in and out over the next 8 to 12 weeks can prevent most cash emergencies. Tools like ProfitBooks can help you track invoices, monitor outstanding receivables, and review expense patterns so you can spot a tightening Profit-to-Cash Gap before it becomes a problem.
Common cash flow and profit mistakes small businesses make
FAQs
Is cash flow the same as profit?
No. Profit measures whether a business earned more revenue than it incurred in expenses over a period, while cash flow tracks the actual movement of money into and out of the business. A business can be profitable without having positive cash flow, and vice versa, because the timing of recording revenue and expenses often differs from when cash is received or paid.
Can a profitable business run out of cash?
Yes. This commonly happens when customers delay payments, when growth requires heavy upfront spending, or when loan repayments consume cash that does not reduce reported profit.
Why doesn't my bank balance match my profit?
Because profit includes revenue you have earned but may not have collected, and it excludes certain cash movements like loan principal repayments and equipment purchases that reduce your bank balance without fully appearing as expenses.
What causes negative cash flow?
Delayed customer payments, large inventory purchases, debt repayments, capital expenditures, and seasonal revenue dips are the most frequent causes for small businesses.
Is cash flow more important than profit?
Both are essential. Cash flow keeps the business operating day to day. Profit determines whether the business model is sustainable over time. Ignoring either one creates risk.
How often should a business monitor cash flow?
Weekly is ideal for small businesses. Monthly at minimum. The earlier you spot a cash shortfall, the more options you have to address it.
Conclusion
The difference between cash flow and profit is not academic. It is the difference between a business that looks healthy and a business that actually is.
Profit tells you the score. Cash flow tells you whether you can stay in the game.
If your business is profitable but you are constantly scrambling to cover bills, start investigating the Profit-to-Cash Gap. Look at your unpaid invoices, your inventory levels, your payment timing, your loan schedule, and your recent purchases. The answer is almost always hiding in one of those five places.
Understand both numbers. Watch both numbers. Your business depends on it.
Watch both numbers, without the spreadsheet scramble
ProfitBooks tracks invoices, receivables, and expenses in one place, so you can review profit monthly and monitor cash flow weekly, and catch the Profit-to-Cash Gap early.