Sales Returns, Refunds & Chargebacks: How Each One Affects Your Revenue and Books
On this page 32 sections
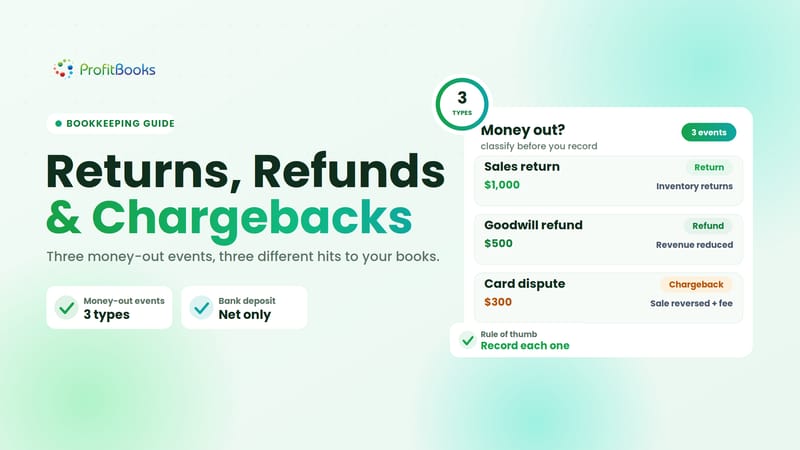
Three transactions can all reduce your bank balance, but they aren't the same
Last month I was reviewing the books of an ecommerce business that had lumped three very different events into a single "adjustments" line: a $1,000 product return, a $500 goodwill refund, and a $300 card dispute. The bank balance dropped by $1,800 total. Clean enough, right?
Not even close. That $1,000 return brought inventory back into the warehouse. The $500 refund didn't, because it was a service credit. And the $300 chargeback carried a separate processor fee the owner hadn't even noticed. Three events, three different impacts on revenue, inventory, cost of goods sold, and cash. Treated identically, they made the P&L almost useless for decision-making.
This is the confusion I run into constantly. A refund and a chargeback can both reverse a payment, but the business event behind them is different. If you record all three as "money out," you lose visibility into what actually happened, why it happened, and what it cost.
This article will walk through each event: what distinguishes a sales return from a refund from a chargeback, how each one touches revenue, inventory, accounts receivable, cash, and processor fees, and why your bank deposit alone can never tell the full story. By the end, you'll understand exactly which accounts move, which records to keep, and what rising reversal rates are actually telling you about your operations.
The short version
A return, a refund, and a chargeback can all shrink your bank balance, but they are different business events that hit different accounts. Record each one on its own, tie the adjustment back to the original transaction, and reconcile it to your processor and bank.
- Return: product comes back, so revenue, inventory, and COGS can all move.
- Refund: you voluntarily send money back, which reduces revenue, not an expense.
- Chargeback: the payment network reverses the sale, and a separate fee almost always applies.
- Your bank deposit is net of fees and reversals, so it never equals gross sales.
- Rising return, refund, and chargeback rates each point to a different operational problem.
Sales return vs refund vs chargeback: what's the difference?
A sales return involves a customer sending a product back. The underlying sale is being reversed or adjusted, and physical goods may re-enter inventory. A credit note is often issued, depending on the transaction type and local requirements.
A refund is money returned to the customer. It may follow a return, but it doesn't have to. Service cancellations, overpayments, billing corrections, and goodwill adjustments can all trigger refunds with no product changing hands.
A chargeback is a payment dispute. The customer (or their card issuer) initiates the reversal through the payment network, not through the business. The processor or issuer withholds or reverses funds, the merchant may respond with a representment packet, and the dispute is resolved in the merchant's favor or against it. Fees almost always apply regardless of outcome.
| Factor | Sales return | Refund | Chargeback |
|---|---|---|---|
| Who initiates? | Customer/business return process | Business/customer agreement | Customer/card issuer |
| Product comes back? | Usually | Not necessarily | Usually no |
| Revenue affected? | Usually | Usually | Usually, if dispute reverses the sale |
| Inventory affected? | Potentially | Depends on underlying sale | Usually no |
| Separate fee? | Rarely | Processing cost may apply | Often yes |
| Reconciliation complexity | Medium | Medium | High |
The 3R test: return, refund or dispute?
ProfitBooks Editorial Framework (not an established accounting standard)
Three questions classify any reversal event:
One transaction can trigger more than one. A customer returns a product (return), you issue money back (refund), and if you're too slow, the customer also files a dispute (chargeback). Each piece needs its own accounting treatment.
Scenario A. Customer ships back a defective item. You credit their account. Return plus refund.
Scenario B. Customer cancels a consulting engagement. You return the deposit. Refund only, no inventory event.
Scenario C. Customer tells their bank they don't recognize a charge. The processor pulls funds from your next settlement. Chargeback, no product returned, and a fee lands on top.
How sales returns affect your books
Revenue impact
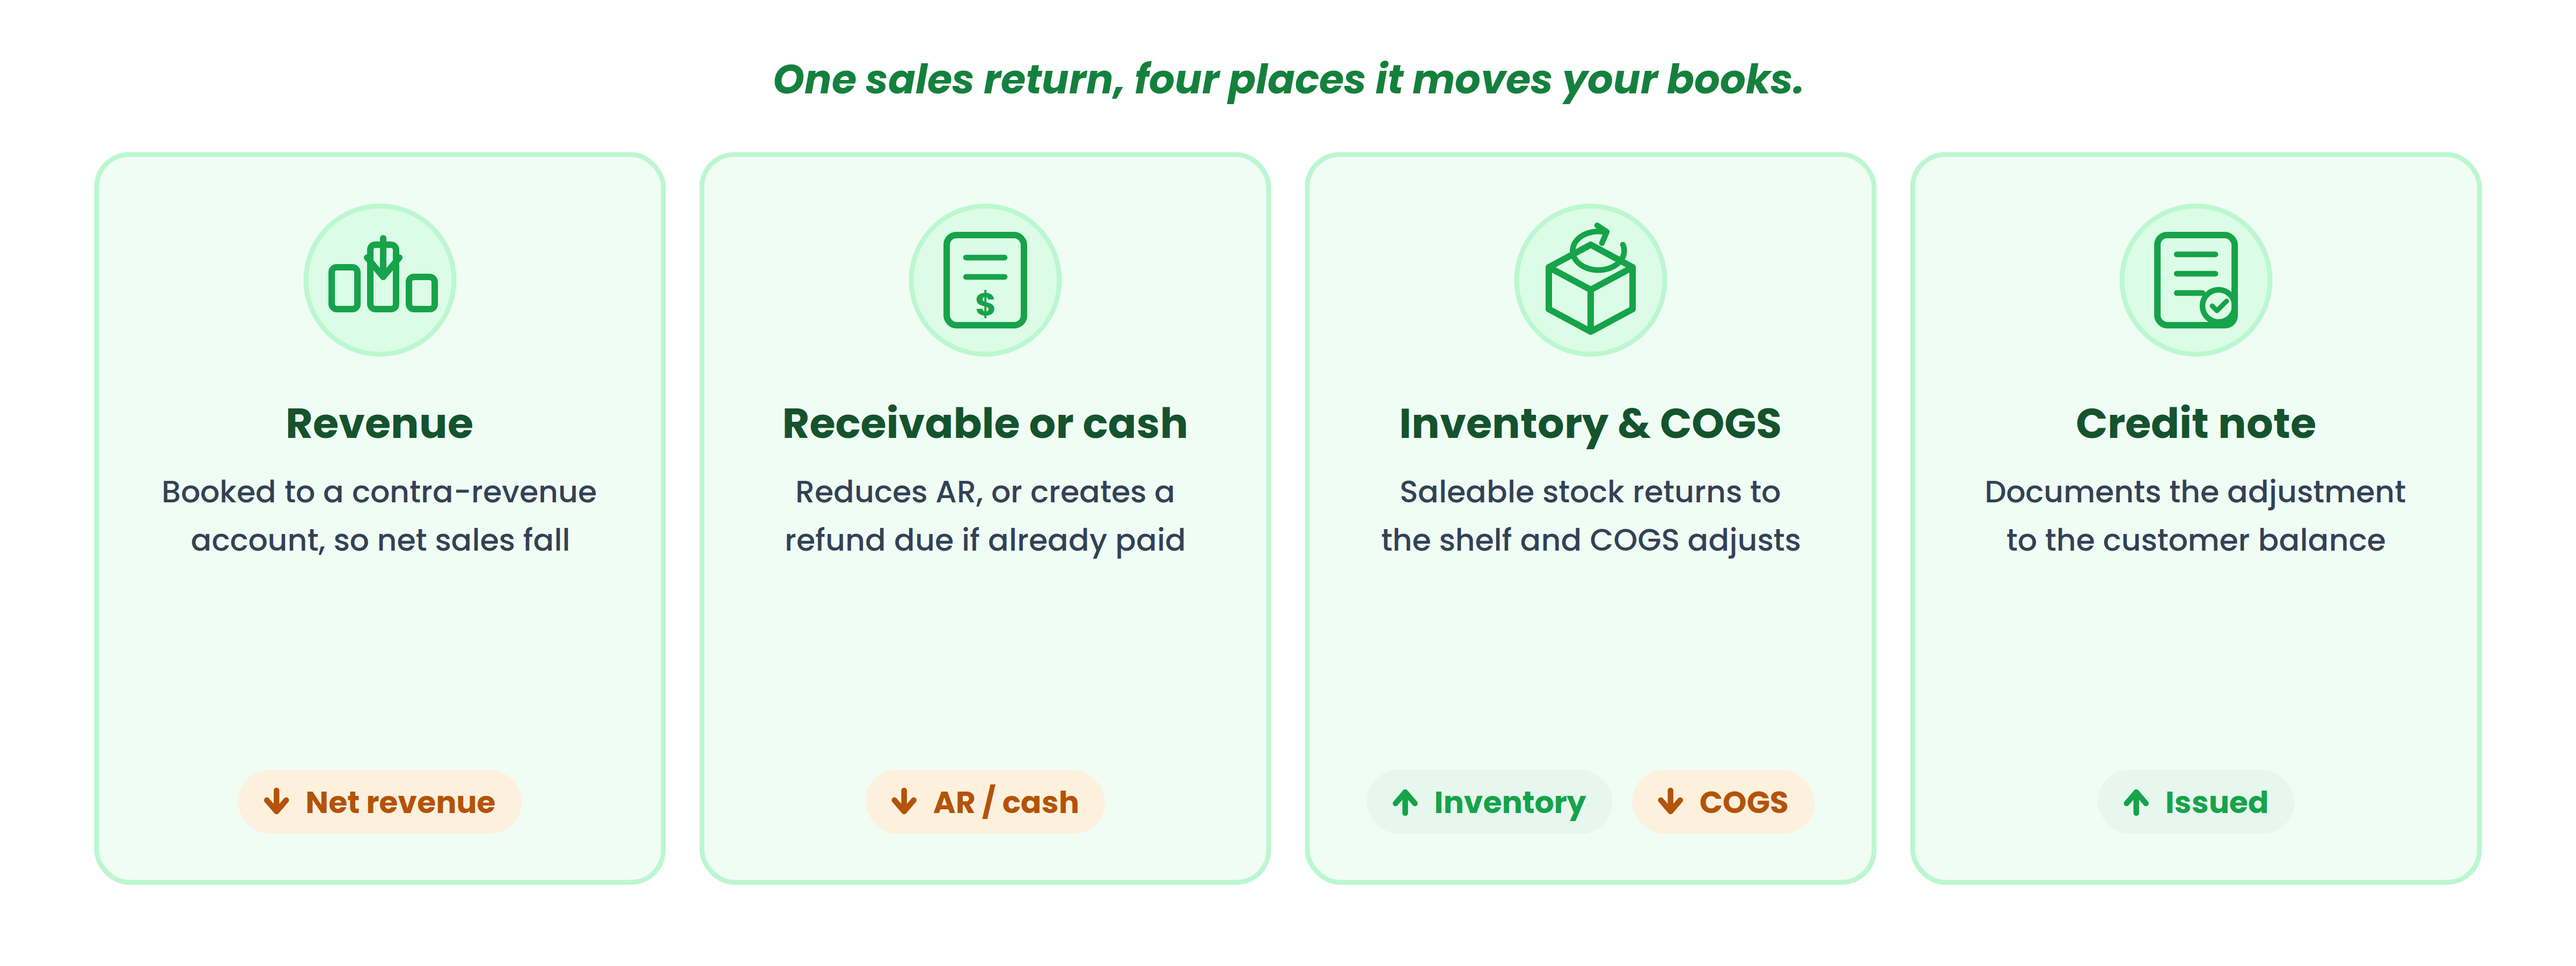
A sales return generally reduces the revenue retained from that sale. Most businesses record this through a contra-revenue account (Sales Returns and Allowances) so gross sales remain visible and net revenue reflects the adjustment. The distinction matters: your gross sales show demand, your net sales show what you actually kept.
Accounts receivable or cash
If the original sale was on credit and unpaid, the return reduces accounts receivable. If the customer already paid by card or cash, the return creates a refund obligation or a credit balance. The mechanics shift depending on whether money has already moved.
Inventory impact
For physical products returned in saleable condition, inventory increases and cost of goods sold is adjusted. If returned goods are damaged, don't automatically put them back at full carrying value. The appropriate treatment depends on the condition and your accounting policy. For services, there's nothing physical to restore.
Credit notes
A credit note documents the adjustment to the customer's balance. When a return or invoice adjustment requires a credit note, the specifics (format, tax treatment, legal requirements) vary by jurisdiction. ProfitBooks has a dedicated guide covering credit notes for returns, damaged goods, overcharges, and pricing adjustments.
How refunds affect your books
Full refund
Original sale: $500. Customer gets $500 back. The revenue from that sale is reversed (or reduced through contra-revenue), and cash or the payment obligation decreases by $500. The original transaction should remain in the ledger with the adjustment linked to it, not deleted.
Partial refund
Original sale: $500. Refund: $100. You keep $400 of recognized revenue. The $100 adjustment should be traceable to the original invoice. Partial refunds are where I see the most cleanup work, because businesses sometimes record them as miscellaneous expenses and lose the connection to the sale entirely.
Refund without a product return
Service cancellations, billing corrections, overpayments. No inventory comes back because there's nothing physical to return. A sales return can affect both revenue and inventory; a service refund generally does not have an inventory component.
Why a refund is not automatically an expense
This trips up a lot of small businesses. A refund generally reverses or reduces revenue. It is not an operating expense like rent or marketing. Recording it as an expense inflates both your top line and your cost structure. The correct presentation depends on your accounting framework and circumstances, but the general principle holds: if you're giving back sales proceeds, that's a revenue adjustment, not a cost of doing business.
Stop lumping returns, refunds, and chargebacks together
ProfitBooks records refund vouchers and credit notes against the original invoice, so each reversal keeps its own trail instead of disappearing into one adjustments line.
How chargebacks affect your books
What happens during a chargeback?
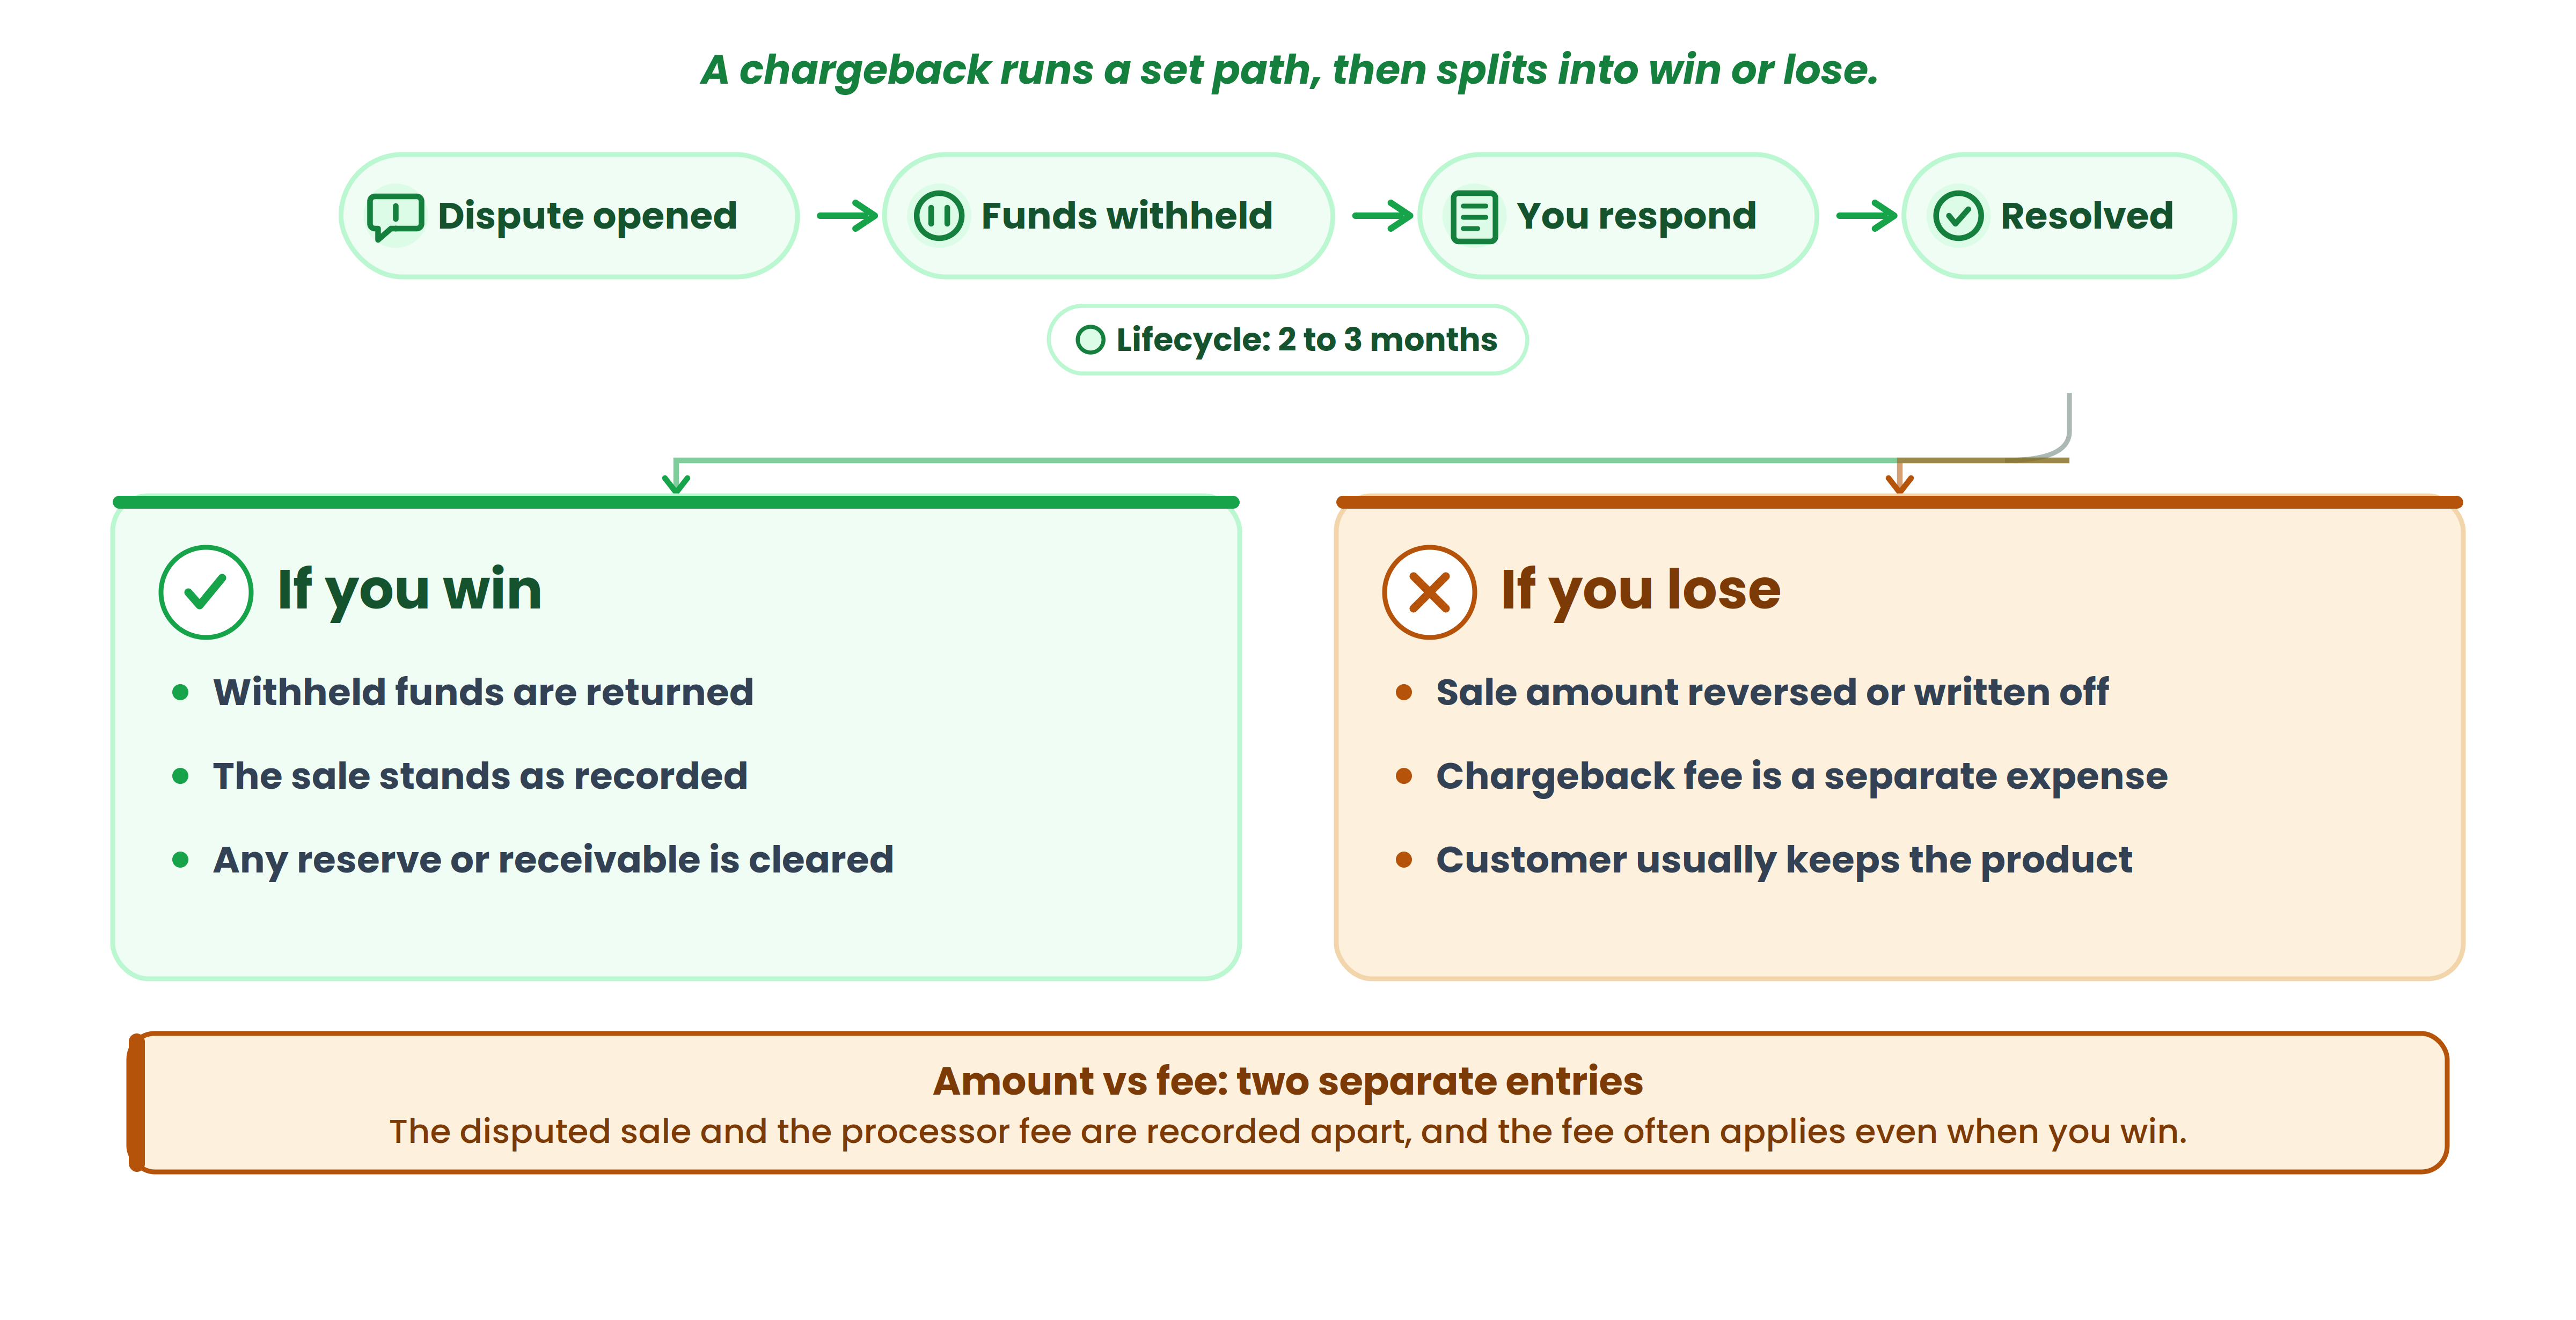
The customer disputes a charge. The card issuer or payment processor opens a case, and the disputed amount may be withheld from your next payout or reversed outright. You can respond with evidence (a representment packet including shipping proof, AVS/CVV data, policy acceptance, and customer communication). The dispute resolves: you either recover the funds or lose them. According to Chargeback.io, the full lifecycle can take two to three months.
Chargeback amount vs chargeback fee
This is critical. The disputed sale amount and the chargeback fee are separate financial events. The disputed amount may reverse the sale. The fee is a cost the processor charges for handling the dispute. Even if you win, the fee often still applies. Mixing these two together in one entry makes your revenue and your expense reports wrong simultaneously.
What happens if you win?
The withheld funds are returned. Your accounting should reflect the recovery: the sale stands, and any interim reserve or receivable is cleared. If you'd already written the amount off, the recovery reverses that entry.
What happens if you lose?
The sale amount is gone. Depending on your accounting policy and framework, the lost amount may be treated as a revenue reversal or as bad debt expense. The chargeback fee is a separate operating expense. And the product? The customer usually keeps it. That's the part that stings most: you lose the revenue, the product, and you pay a fee.
Returns, refunds and chargebacks: financial impact compared
| Factor | Sales return | Refund | Chargeback |
|---|---|---|---|
| Customer receives money? | Usually | Yes | Potentially |
| Revenue affected? | Usually | Usually | Usually, if lost |
| Inventory affected? | Potentially | Depends | Usually no |
| Processor involved? | Not necessarily | Often | Yes |
| Separate fee? | Rarely | May apply | Often |
| Credit note? | May be | Depends on transaction | Not typically |
Actual treatment depends on the transaction, payment method, accounting framework, and jurisdiction.
Gross sales vs net sales: why returns can hide in your numbers
Gross sales minus returns, allowances, and refunds equals net sales. Simple formula, enormous implications.
Example: Gross sales of $100,000. Returns and refunds of $6,000. Net sales: $94,000.
If you only track net deposits, you can't see that $6,000. You can't calculate a return rate. You can't spot a product quality problem. Beancount.io illustrates this well: a business with $4,000,000 in December sales expecting a 5% return rate would recognize roughly $3,800,000 of revenue and a $200,000 refund liability, with an estimated $80,000 of inventory cost expected back from returns.
Why simply looking at bank deposits doesn't work
A bank deposit is a cash movement, not necessarily a complete record of gross sales. Your payment processor deducts refunds, chargebacks, chargeback fees, and processing fees before depositing the net payout. If you book only the deposit amount, your gross sales are understated and your fee visibility is zero. Blue Onion's 2026 guidance emphasizes recording gross transactions rather than waiting for every return to happen.
The inventory side of sales returns
When you sell a physical product, inventory decreases and COGS increases. When the product comes back in saleable condition, you reverse that: inventory goes up, COGS adjusts down.
Damaged returns are different. You can't put a broken item back at full value. Write-down or disposal treatment depends on the condition and your policy. For service businesses, there is no inventory to restore.
This distinction matters most for retailers, ecommerce sellers, and distributors where inventory management directly affects reported margins.
Why payment processor reconciliation gets complicated
Here's the flow: gross transaction, minus processor fees, minus refunds, minus chargebacks, minus chargeback fees, minus other adjustments, equals net payout, equals bank deposit.
That's why your bank deposit almost never matches your daily sales total. A clearing account (a temporary holding account in your ledger) helps bridge the gap. You record the gross sale, then reconcile the processor's settlement report line by line against what actually landed in the bank. Patriot Software's 2026 guidance recommends mapping each event (sale, refund, chargeback) to the ledger separately, then reconciling to processor records.
If your clearing account doesn't trend toward zero after reconciliation (with only timing differences remaining), something is misclassified.
How returns and refunds affect business metrics
Return rate: Returns ÷ Gross Sales × 100. Businesses define the numerator differently (transactions, units, or monetary value), so pick one definition and stick with it.
Chargeback rate matters even more. If your ratio of chargebacks to card transactions rises high enough, processors may impose a settlement reserve, which is essentially a cash-flow tax on your business. Your chargeback ratio matters more than your chargeback volume.
These rates feed directly into net revenue, gross margin, and contribution margin.
What do rising returns, refunds or chargebacks tell you?
Rising product returns may point to quality issues, inaccurate product descriptions, sizing problems, or fulfillment damage. Rising refunds could signal service dissatisfaction, billing confusion, or cancellations. Rising chargebacks may indicate fraud concerns, unclear billing descriptors, shipping delays, or customer-service failures.
One mistake I see often: treating chargebacks as random one-off events. They're usually symptoms. If multiple customers say "I don't recognize this charge," the problem isn't the dispute process. It's your billing descriptor.
Common accounting mistakes with returns, refunds and chargebacks
The fix for most of these is the same: record each component separately and tie adjustments back to the original transaction.
A practical tracking framework
For every return, refund, or chargeback, capture:
| Field | Example |
|---|---|
| Original transaction | INV-1045 |
| Event type | Refund |
| Amount | $150 |
| Reason | Product defect |
| Date | 2026-08-10 |
| Payment method | Card |
| Status | Completed |
| Inventory impact | Yes |
| Fee | $0 |
| Accounting adjustment | Contra-revenue |
| Reconciled | Yes |
The "reason" field is the one most businesses skip. Without it, you can't diagnose patterns.
What businesses should keep
Original invoice, credit note (where applicable), refund confirmation, return authorization, shipping documentation, processor transaction ID, chargeback notification, dispute evidence bundle, settlement reports, bank statements, and customer communication. Retention requirements vary by jurisdiction.
What to look for in accounting software
| Capability | Why it matters |
|---|---|
| Credit notes | Adjust customer and invoice balances |
| Refund recording | Track money returned with traceability |
| Inventory handling | Reflect returned stock accurately |
| Sales reports | Show gross and net activity separately |
| Customer ledger | Maintain full transaction history |
| Tax reporting | Reflect applicable adjustments |
| Reconciliation | Match processor and bank activity |
| Audit trail | Preserve every change |
How ProfitBooks handles refunds, credit notes and sales data
ProfitBooks supports refund vouchers (with customer, date, payment account, amount, and payment mode), credit notes linked to invoices, and 45+ exportable financial reports covering sales, customer balances, and tax data. For chargebacks specifically, ProfitBooks helps you organize the underlying sales and refund records that feed into your dispute response. The accounting records and cash flow visibility give you what you need to reconcile processor settlements against your ledger.
Frequently asked questions
What is the difference between a sales return and a refund?
A sales return means the customer sends the product back, which may restore inventory and adjust COGS. A refund means money goes back to the customer, but no product necessarily returns. A return often triggers a refund, but refunds also happen independently (service cancellations, billing corrections, goodwill credits). They affect different accounts.
Is a refund an expense or a reduction in revenue?
Generally a reduction in revenue, not an operating expense. You're reversing sales proceeds, not incurring a new cost. Recording refunds as expenses overstates both your top line and your cost structure.
What is the difference between a refund and a chargeback?
A refund is merchant-initiated. A chargeback is a forced reversal through the payment network, initiated by the customer or card issuer, and it typically carries a separate fee.
Does a sales return affect inventory?
For physical products returned in saleable condition, yes. Inventory increases and COGS adjusts. Damaged returns require different treatment. Service businesses have no inventory impact.
Do chargebacks affect revenue?
If the dispute is lost, the sale amount is reversed or written off, which reduces revenue or creates a bad debt expense depending on accounting policy.
Are chargeback fees an expense?
Yes. The fee is a separate operating cost, distinct from the disputed sale amount.
Does a credit note mean the customer has received a refund?
Not necessarily. A credit note adjusts the customer's balance on your books. The actual payment (refund) may happen separately or the credit may be applied to a future invoice.
Why don't payment processor deposits match sales?
Processors deduct fees, refunds, chargebacks, and chargeback fees before depositing the net payout. The deposit reflects cash movement, not gross sales.
How do partial refunds affect accounting?
The original sale stays on the books. The partial refund reduces recognized revenue by the refunded amount only. Both entries should be traceable to the same transaction.
How should businesses track returns and refunds?
Record each event with the original transaction reference, event type, amount, reason, inventory impact, fee, and reconciliation status. The reason field is what turns raw data into operational insight.
Don't treat every money-out transaction the same
A return, a refund, and a chargeback can all shrink what lands in your bank account. They are not interchangeable.
Return: something came back. Refund: you voluntarily sent money back. Chargeback: the payment system reversed or disputed the transaction.
Record each one. Categorize it correctly. Reconcile it to your processor and your bank. Then analyze the patterns, because a rising return rate and a rising chargeback rate are telling you very different things about your business. The next problem most businesses hit after getting this right is period-end cutoff: making sure reversals land in the same reporting period as the original sale. That's where clean tracking pays off the most.
Spending too much time matching processor payouts to your books?
ProfitBooks tracks refund vouchers, credit notes, and sales data in one place so reconciliation doesn't eat your afternoon.