Business Budgeting for Small Businesses: How to Create a Budget That Actually Works
On this page 29 sections
A business owner I worked with closed the year at ₹1.2 crore in revenue. Impressive number. The kind you'd celebrate at a team dinner.
But when we sat down to look at where the money actually went—rising vendor costs, three unplanned equipment purchases, a marketing campaign that ran two months longer than it should have, and receivables stuck in a 90-day cycle—there was almost nothing left.
The business didn't have a revenue problem. It had a budgeting problem.
And honestly, that's the pattern I see over and over. Businesses don't fail because they can't sell. They fail because they spend without a framework, react instead of plan, and treat budgeting as a once-a-year formality instead of what it actually is: a continuous decision-making system.
By the end of this guide, you'll know how to build a business budget grounded in real operations, run monthly budget-to-actuals reviews, spot variances before they become crises, and choose the right budgeting approach for your specific business.
What Is a Business Budget?
A business budget is a financial plan that estimates expected income, expenses, and cash flow over a specific period. It helps businesses allocate resources, control spending, measure performance, and make informed financial decisions.
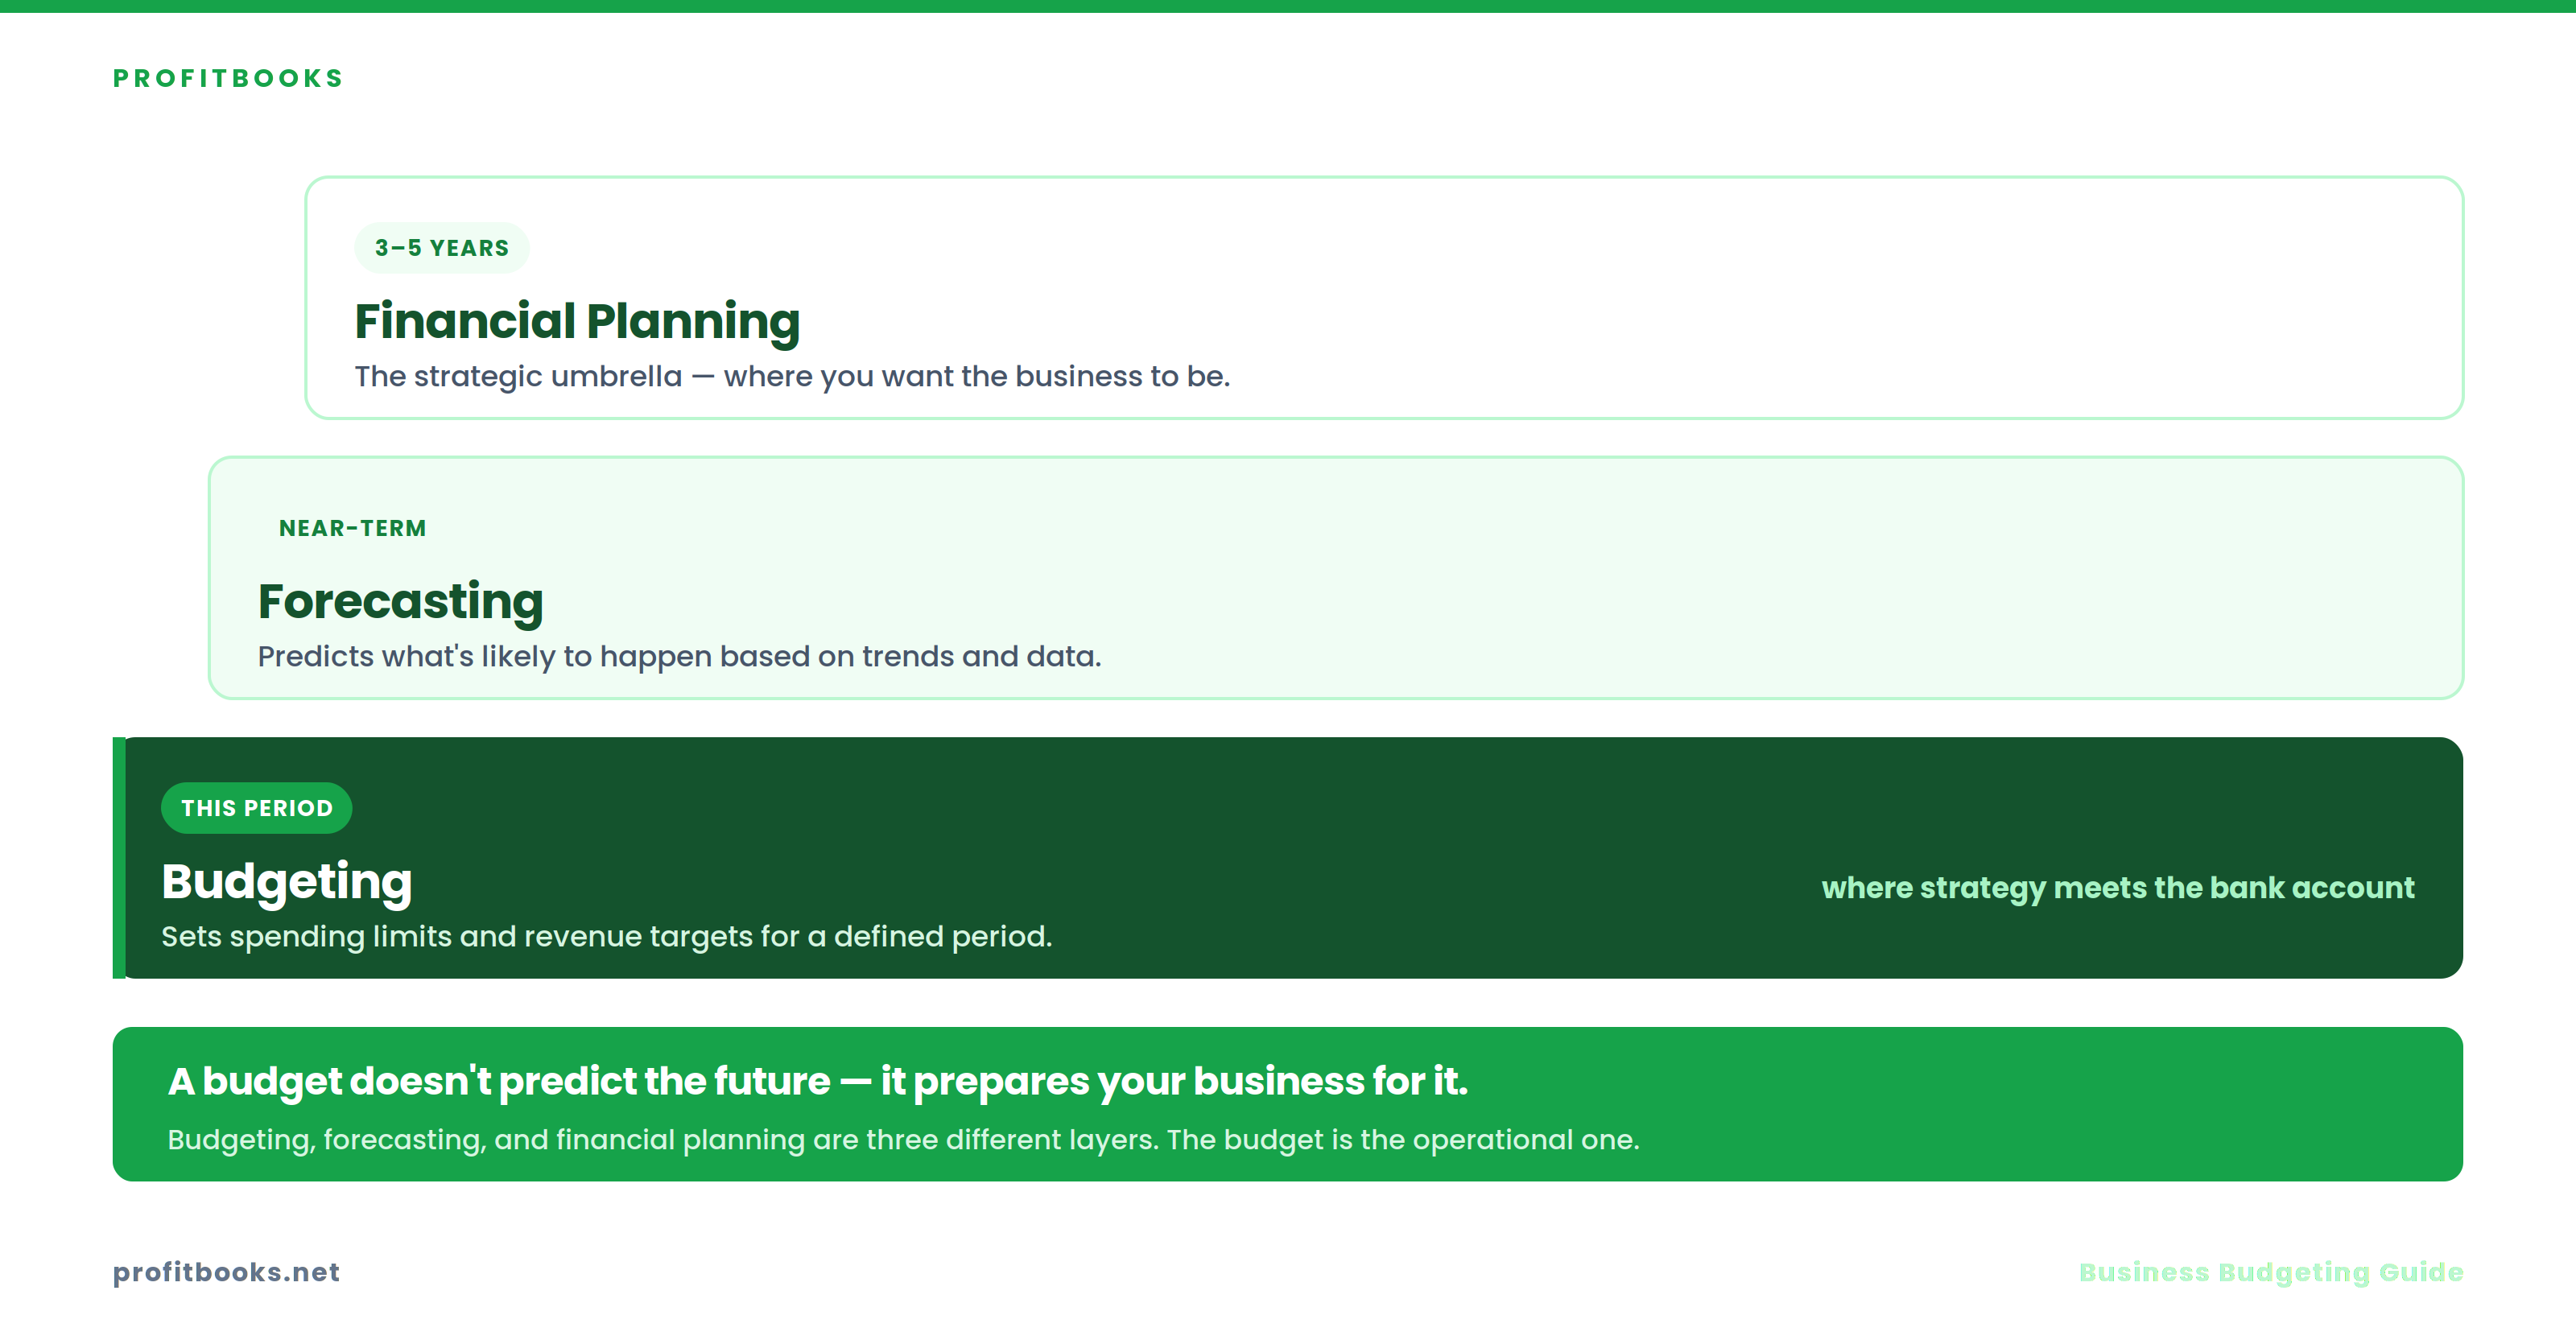
Here's a distinction most articles blur: budgeting, forecasting, and financial planning are not the same thing.
- Budgeting sets spending limits and revenue targets for a defined period.
- Forecasting predicts what's likely to happen based on trends and data.
- Financial planning is the broader strategic umbrella—where you want the business to be in three to five years.
A budget is the operational layer. It's where strategy meets the bank account.
A budget doesn't predict the future—it prepares your business for it.
Why Every Small Business Needs a Budget
Short answer: Without a budget, you're making financial decisions based on gut feeling and bank balance glances. That works until it doesn't.
Here's what a working budget actually gives you:
Expense control. A retailer I advised was spending ₹45,000/month on software subscriptions across six tools—three of which nobody had logged into in months. Those are zombie costs. A budget review caught them. A bank statement never would have.
Cash flow visibility. A manufacturing unit with healthy quarterly revenue nearly missed payroll because their receivables cycle stretched to 75 days while payables were due in 30. Profitability on paper means nothing if cash isn't available when you need it. Understanding your accounts payable vs accounts receivable cycle is non-negotiable.
Loan and investor readiness. Banks don't just want to see revenue. They want to see that you understand your fixed vs. variable mix, your break-even point, and your cash flow coverage. A budget signals financial discipline.
Planning confidence. When you know your numbers, hiring decisions, inventory purchases, and marketing spend stop being anxiety-inducing gambles. They become calculated moves.
Step-by-Step Guide to Creating a Business Budget
Pre-flight check: Before you start, you need 12 months of historical financial data (or industry benchmarks if you're a startup), a clear chart of accounts, and access to your bank and accounting records.
Stop/Go test: Can you state your top three business goals for the next 12 months in one sentence each? If not, start there.
Phase 1: Set Business Goals
Every budget line should trace back to a goal. Revenue growth of 15%? That changes your marketing allocation. Want to reduce debt? That changes how you prioritize loan repayments over capital expenditure.
Use SMART goals. Not because it's trendy—because vague targets produce vague budgets.
Phase 2: Estimate Revenue
Pull your last 12 months of sales data. Identify your best month and your worst month.
The Revenue Reality Test: If your projected revenue is more than 20% higher than your worst month, you're likely overestimating. Deflate your projection by 10% as a cushion ratio before finalizing. Revenue overestimation is the single most common reason small business budgets collapse by Q2.
For seasonal businesses—retail during Diwali, tourism during summer—map revenue month by month, not as an annual average.
Phase 3: Calculate Fixed Expenses
These don't change with sales volume: rent, salaries, insurance, loan EMIs, annual software licenses.
The Fixed Cost Lock Test: If your fixed costs aren't 100% covered by your most conservative revenue estimate, stop. You have a structural problem that no budget can solve—you need to restructure costs or rethink pricing.
Phase 4: Estimate Variable Expenses
Raw materials, shipping, commissions, packaging, transaction fees. These scale with activity.
The 10% Rule: Inflate every variable cost estimate by 10%. Businesses rarely overspend because of one large purchase. Small unplanned expenses accumulated over months often have a bigger impact. That 10% buffer absorbs the friction.
Phase 5: Budget Payroll
Salaries, benefits, bonuses, contractor payments. For a service business, this might be 60-70% of total costs. Don't forget statutory contributions—PF, ESI, gratuity provisions.
Phase 6: Plan for Taxes
GST, income tax, TDS—these aren't surprises. They're predictable obligations. Budget them monthly so you're not scrambling during filing season. Reviewing your financial reports monthly helps you stay ahead of compliance.
Phase 7: Set Aside Emergency Funds
Maintain a cushion ratio of 5-10% of monthly revenue. The contingency fund saved one of my clients when their primary vendor went bankrupt and they needed to source materials at a premium for two months.
Phase 8: Allocate Growth Investments
Marketing campaigns, new equipment, hiring, product development. This is where trade-offs get real:
- Cutting marketing may improve short-term margins but slow future pipeline.
- Reducing inventory improves cash flow but increases stockout risk.
- Hiring increases expenses today but supports revenue capacity tomorrow.
A budget should guide business decisions, not restrict business growth.
Phase 9: Forecast Cash Flow
Revenue minus expenses tells you profitability. But when money arrives and when it leaves tells you whether you can actually operate. If your cash flow coverage drops below three months of operating expenses, freeze non-essential variable spending immediately.
For businesses managing complex payment cycles, understanding why outstanding payments get stuck can be the difference between liquidity and crisis.
Phase 10: Review and Adjust—Monthly
This is where most budgets die. They get created in January and forgotten by March. Budget drift by month three is almost universal when there's no review rhythm.
Visual checkpoint: Your budget dashboard should show variance bars within ±5% for fixed costs. If you're seeing double-digit swings, your estimates need reforecasting.
Simplify Your Budget Reviews
Tracking expenses manually across spreadsheets makes monthly reviews painful. ProfitBooks automates expense tracking and budget-vs-actual reporting, giving you real-time visibility without the reconciliation headaches.
Common Budget Categories Every Business Should Track
The Login Audit: Manually check login activity for every software subscription. If nobody has logged in for 30 days, cancel it. "We might need it later" is how zombie costs bleed your budget dry.
Budget vs Actual: How to Measure Business Performance
Budgeting is only valuable if actual results are reviewed against planned targets. This is variance analysis—the practice that separates businesses that budget from businesses that budget well.
Monthly review workflow:
The 5-Point Random Check: Verify five random expense entries against bank statements. If three or more are wrong or misclassified, your data is dirty—stop and reconcile before drawing conclusions.
Keeping your books clean through regular bank reconciliation makes variance analysis reliable instead of guesswork.
Budgeting Mistakes That Hurt Small Businesses
Annual vs Rolling Budgets: Which Approach Fits Your Business?
A distributor dealing with fluctuating procurement costs and logistics expenses benefits from rolling forecasts. A professional services firm with predictable retainer revenue might do fine with an annual budget reviewed quarterly.
Fixed vs Flexible Budgets
A manufacturer budgeting ₹5 lakh/month for raw materials at 1,000-unit production needs a flexible model. If orders jump to 1,400 units, the budget should scale proportionally—otherwise you're comparing apples to oranges in your variance analysis.
Excel Budgets vs Accounting Software
The core problem with spreadsheets isn't capability—it's data silos. When your budget lives in one file and your actuals live in your accounting system, reconciliation becomes a manual, error-prone chore. Building the budget inside your accounting software eliminates that gap entirely.
How Accounting Software Supports Better Budgeting
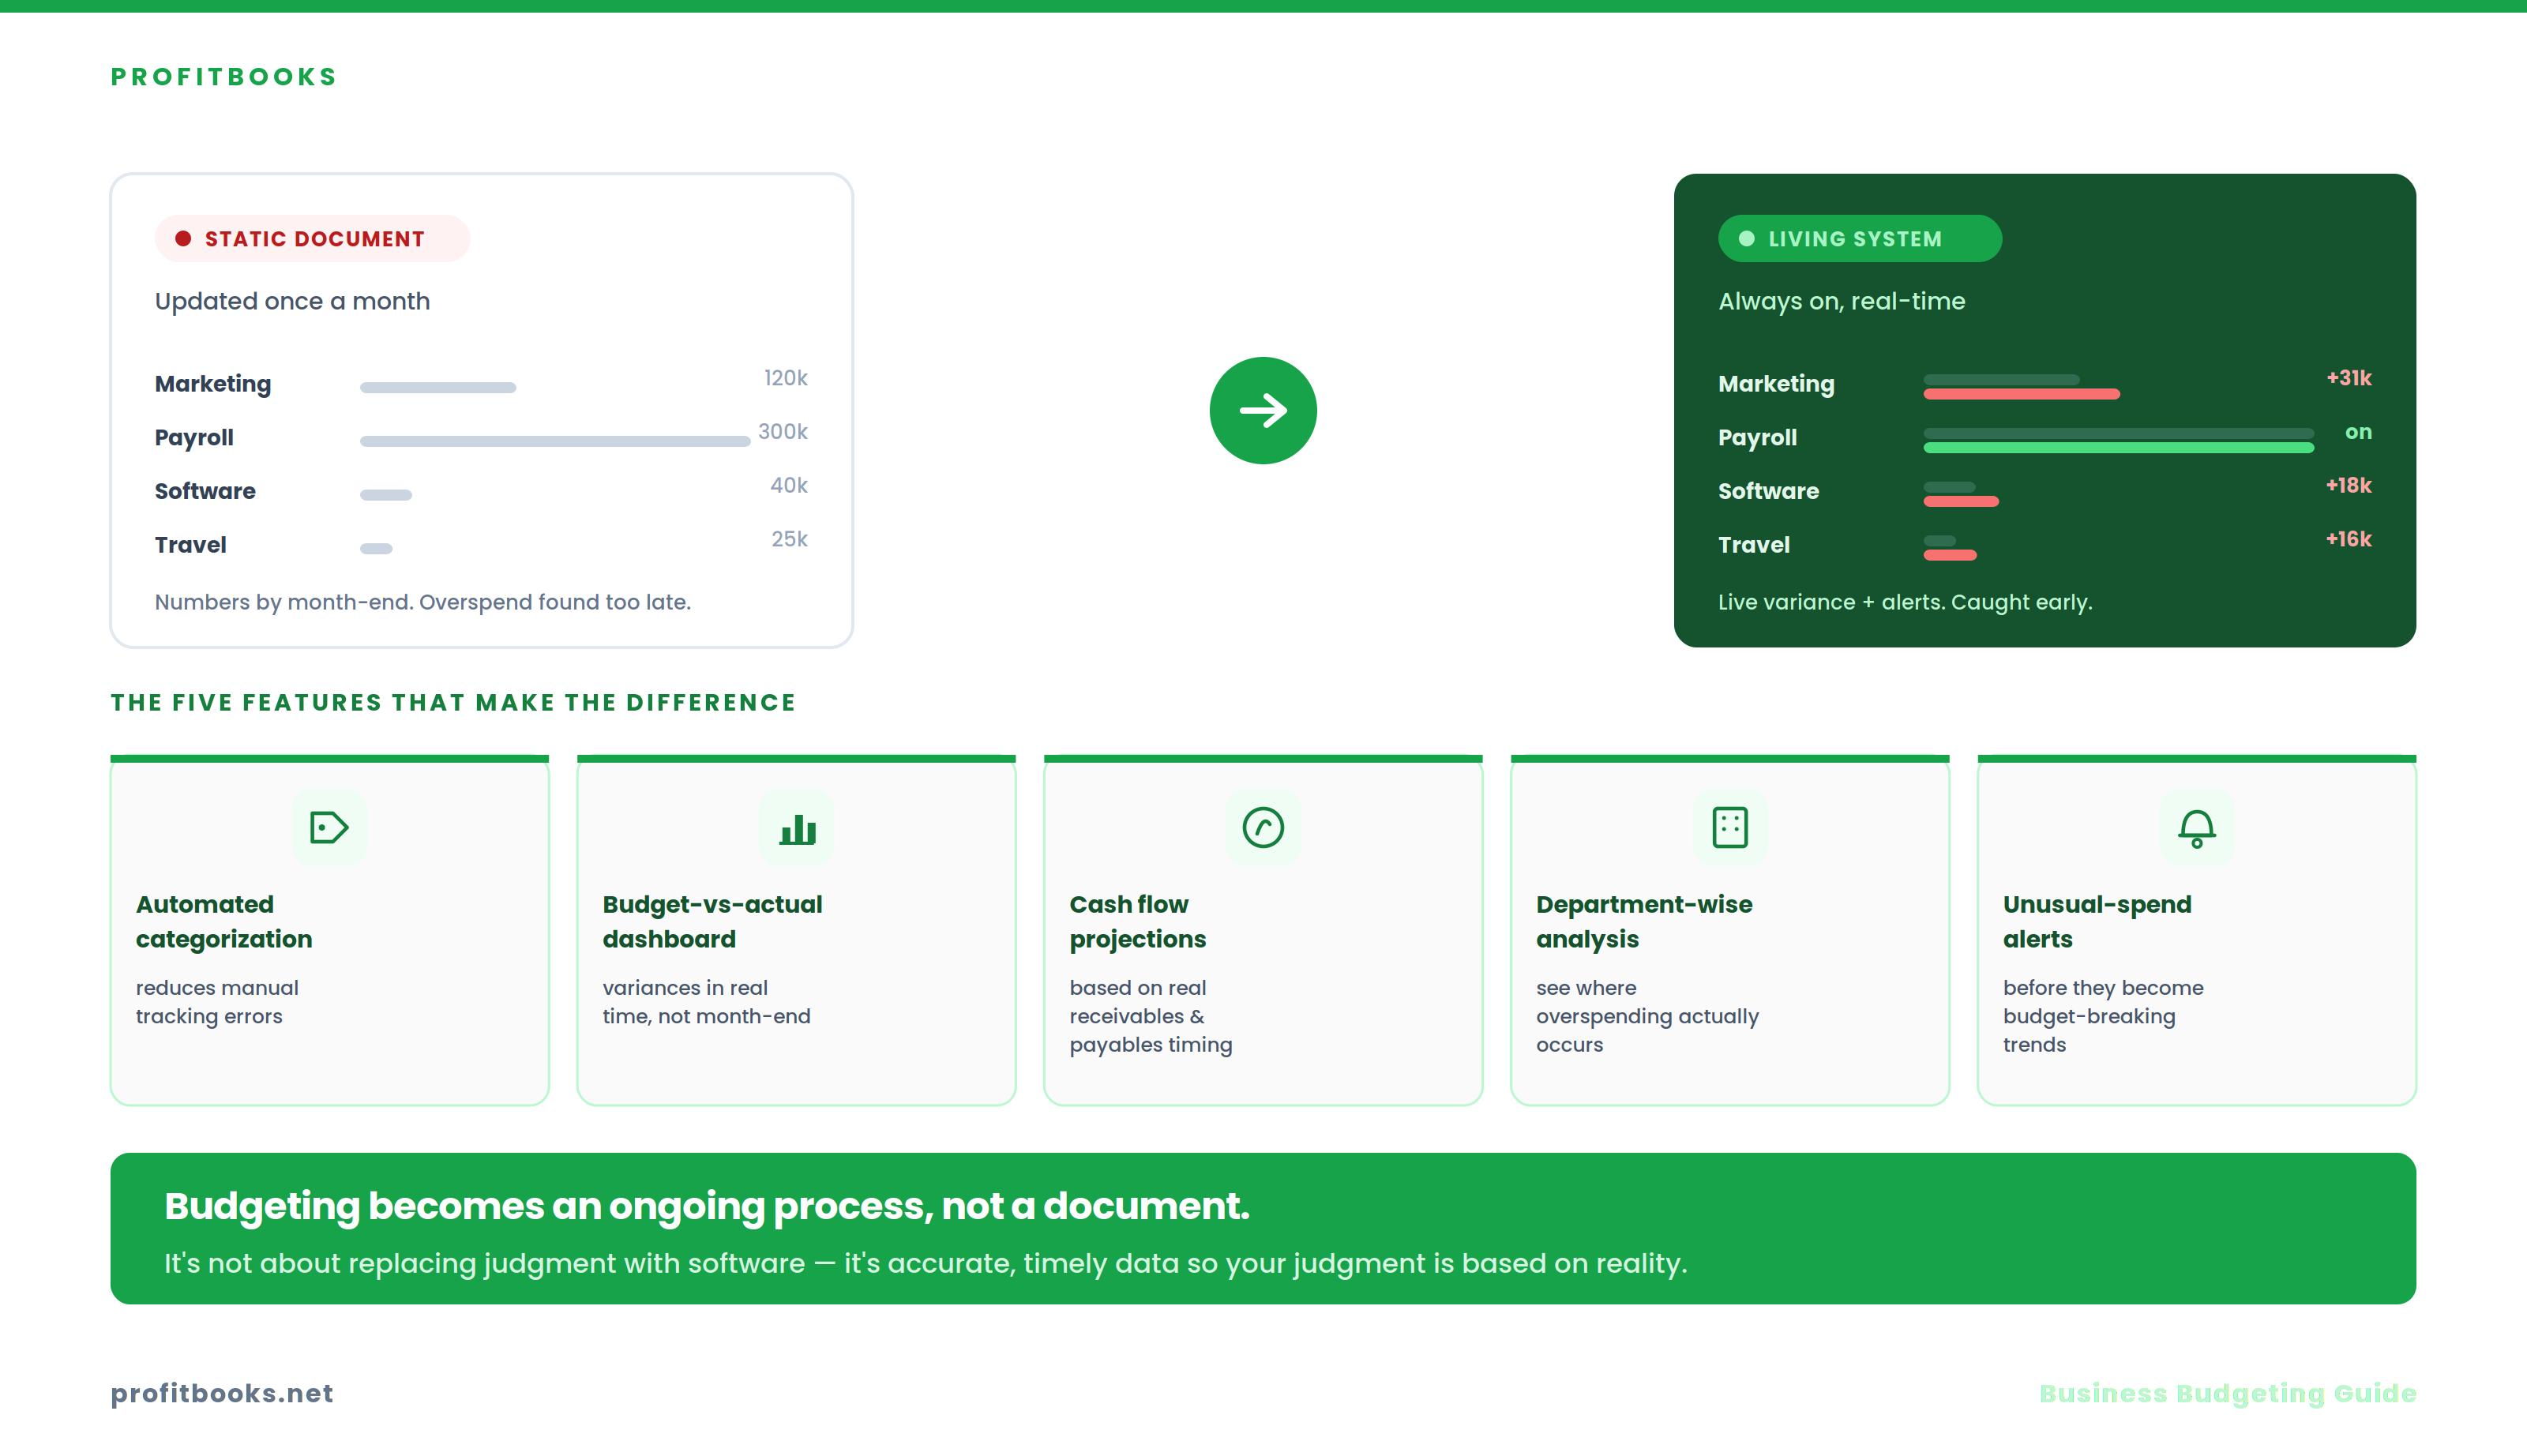
Modern accounting platforms offer features that make budgeting an ongoing process rather than a document:
- Automated expense categorization reduces manual tracking errors.
- Budget-vs-actual dashboards show variances in real time—not at month-end.
- Cash flow projections based on actual receivables and payables timing.
- Department-wise analysis so you can see where overspending actually occurs.
- Alerts for unusual spending patterns before they become budget-breaking trends.
This isn't about replacing financial judgment with software. It's about giving yourself accurate, timely data so your judgment is based on reality, not assumptions.
Business Budget Preparation Checklist
- ☐ Define 3-5 SMART financial goals
- ☐ Gather 12 months of historical financial data
- ☐ List all fixed expenses with current amounts
- ☐ Estimate variable expenses with 10% buffer
- ☐ Calculate total payroll including statutory costs
- ☐ Map tax obligations by month
- ☐ Set contingency fund at 5-10% of revenue
- ☐ Allocate growth investment budget
- ☐ Build month-by-month cash flow forecast
- ☐ Assign budget ownership to a person or team
Monthly Budget Review Checklist
- ☐ Pull actual income and expense figures
- ☐ Compare actuals against budget line by line
- ☐ Flag variances above threshold (5% fixed, 15% variable)
- ☐ Identify root causes for significant variances
- ☐ Run the 5-point random check on expense entries
- ☐ Calculate current run rate and cash flow coverage
- ☐ Decide: reforecast or adjust spending
- ☐ Document decisions and action items
FAQs
How often should a small business review its budget?
Review budget-to-actuals monthly. Hold a 30-minute reforecast session on the first Monday of each month. Annual-only reviews miss early warning signs—by the time you catch a problem at year-end, the damage is already done.
What is the difference between a fixed and flexible budget?
A fixed budget stays constant regardless of business activity. A flexible budget adjusts targets proportionally as sales or production volumes change, making variance analysis more meaningful for businesses with fluctuating demand.
Can a startup create a budget without historical data?
Yes. Use industry benchmarks, competitor pricing research, and conservative revenue estimates. Apply the 10% rule—inflate costs, deflate revenue projections—and reforecast monthly as real data comes in.
What is budget vs actual analysis?
It's the process of comparing planned financial figures against real performance to identify variances. Revenue, expense, profit, and cash flow variances each signal different operational issues requiring different corrective actions.
How does accounting software help with budgeting?
It eliminates manual data entry, auto-syncs actuals with budgeted figures, generates real-time variance reports, and provides cash flow visibility that spreadsheets can't match at scale.
The businesses that budget well aren't the ones with the fanciest spreadsheets. They're the ones that treat the budget as a living operational tool—reviewed monthly, adjusted quarterly, and used daily to make better decisions.
Ready to move beyond spreadsheets?
Start with ProfitBooks free and get automated budget tracking, real-time financial reports, and cash flow insights built for small business owners who'd rather run their business than wrestle with formulas.